Choosing a robo advisor investment account usually means comparing automated portfolio management, goal planning, fees, and how much control you retain. The five products supplied for this guide are books, not investment accounts, so none can open an account, manage a portfolio, or replace advice from a qualified professional. I’ve ranked them as research and learning resources for readers deciding what to investigate before choosing a real provider.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
FinTech Innovation is my strongest broad introduction to robo-advisors alongside goal-based investing and gamification. The Little Book of Robo Investing is the more direct, concise starting point for readers focused on automated investing, while Fire the Fees is aimed at DIY investors interested in building a plan with AI. The tradeoff is that the supplied details are sparse: there is no verified account comparison, fee analysis, or evidence about each book’s depth. I’d use these titles to frame questions, then confirm account features directly with providers.
Key Takeaways
- None of these five products is a robo-advisor account; they are books about investing, personal finance, or financial technology.
- FinTech Innovation earns the broadest educational role because its supplied description explicitly covers robo-advisors, goal-based investing, and gamification.
- The Little Book of Robo Investing is the most direct title for readers who want a concise introduction to automated investing, though its depth is not documented.
- Fire the Fees is positioned for DIY investors interested in AI-supported plan building, but the supplied information does not verify its methods or advice.
- Before opening an account, compare actual providers on portfolio construction, advisory fees, account minimums, tax features, and human support; these books do not supply those comparisons.
| FinTech Innovation: From Robo-Advisors to Goal-Based Investing and Gamification |  | Best Overall for a Broad Robo-Advisor Primer | Product type: Book | Series: The Wiley Finance Series | Named topic: Robo-advisors | VIEW LATEST PRICE | See Our Full Breakdown |
| The Little Book of Robo Investing: How to Make Money While You Sleep |  | Best Direct Introduction to Robo Investing | Product type: Book | Format: Book; specific format not supplied | Stated subject: Robo investing | VIEW LATEST PRICE | See Our Full Breakdown |
| Using AI for Personal Finance: Budget Bots and Investment Advisors (AI in Everything Everywhere) |  | Best for Connecting Budgeting and Investing | Product type: Book | Series: AI in Everything Everywhere | Named topic: AI for personal finance | VIEW LATEST PRICE | See Our Full Breakdown |
| Fire the Fees: Be Your Own Financial Advisor — Build a Professional Investment Plan with AI |  | Best for DIY Investors Exploring AI Planning | Product type: Book, inferred from title and supplied description | Stated audience: Everyday investors | Stated focus: Building an investment plan | VIEW LATEST PRICE | See Our Full Breakdown |
| AI, FinTech, and the Future of Robo-Advisory: Risk Management and Ethical Considerations | 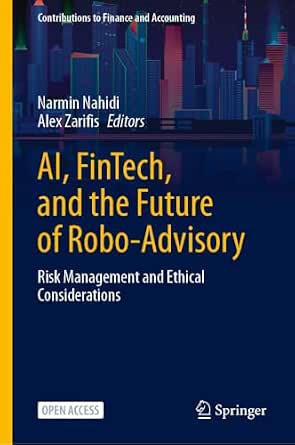 | Best for Risk and Ethics Perspectives | Product type: Book | Series: Contributions to Finance and Accounting | Named topic: AI and FinTech | VIEW LATEST PRICE | See Our Full Breakdown |
| robo advisor investment account | Named topic | Product type | Account service | ASIN |
|---|---|---|---|---|
| FinTech Innovation: From Robo- | Robo-advisors | Book | Not an investment account | B01IRXK6CS |
| The Little Book of Robo Invest | — | Book | Not an investment account | 1394225229 |
| Using AI for Personal Finance: | AI for personal finance | Book | Not an investment account | B0FR2J848G |
| Fire the Fees: Be Your Own Fin | — | Book, inferred from title and supplied description | Not an investment account | B0H9HS7HYS |
| AI | AI and FinTech | Book | Not an investment account | B0H98LDKHP |
More Details on Our Top Picks
FinTech Innovation: From Robo-Advisors to Goal-Based Investing and Gamification
I put FinTech Innovation first because it has the clearest connection to the decisions behind robo-advisor accounts: the supplied description directly names robo-advisors and pairs them with goal-based investing. That gives a reader a wider frame than a book focused only on automated investing. Gamification is another named subject, which may help readers think critically about how digital investment services present choices and encourage engagement.
Compared with The Little Book of Robo Investing, this title appears broader rather than narrowly focused on automated strategies. That breadth is useful if I want to understand how financial technology shapes account design, but it may be less direct for someone who simply wants a short, practical introduction. The supplied information does not say whether the book offers provider comparisons, portfolio examples, or step-by-step account guidance, so I would not treat it as a substitute for current account research.
Its Wiley Finance Series designation identifies a finance-focused series, but the available details do not establish the book’s level, length, or currency. I see it as the best starting point in this lineup for readers who want a conceptual foundation and can follow up with provider disclosures. Skip it if you need a current checklist of account fees, tax-loss harvesting, minimum balances, or customer-service options; none of those details is confirmed here.
Pros:- Explicitly covers robo-advisors
- Adds goal-based investing to the discussion
- Includes gamification as a financial-technology topic
- Identified as part of The Wiley Finance Series
Cons:- The supplied description does not confirm practical account-selection tools
- No information is provided about format, length, examples, or currentness
Best for: Readers who want a broad finance-technology introduction that explicitly includes robo-advisors and goal-based investing.
Not ideal for: Investors seeking a current, practical account comparison, verified provider fees, or a step-by-step setup guide.
- Product type:Book
- Series:The Wiley Finance Series
- Named topic:Robo-advisors
- Named topic:Goal-based investing
- Named topic:Gamification
- Account service:Not an investment account
- Format and length:Not specified in supplied details
- ASIN:B01IRXK6CS
Our verdict“I rank it first for the broadest confirmed coverage of robo-advisors and related investing concepts, while treating it as background reading rather than an account-buying tool.”
The Little Book of Robo Investing: How to Make Money While You Sleep
The Little Book of Robo Investing is the most plainly focused title in this group for readers who want to understand automated investing itself. The supplied description says it covers robo investing and how automated strategies may support wealth-building over time. Its concise-book positioning also suggests a more approachable entry point than FinTech Innovation, whose scope extends into goal-based investing and gamification.
That directness is its main advantage, but the available detail is thin. There is no supplied table of contents, author information, publication context, or confirmation that it explains how actual robo-advisor accounts differ. The subtitle should not be read as a guarantee of investment results; automated strategies still involve market risk, and outcomes depend on a reader’s circumstances and choices. Compared with Fire the Fees, this title appears less focused on building a personal plan with AI and more centered on the general idea of robo investing.
I’d choose it when I want a potentially concise starting point before learning about provider-specific features. I would skip it if I need detailed account comparisons or a documented treatment of taxes, risk questionnaires, human advice, or fees. Those practical account-selection details are not established by the supplied product information.
Pros:- Its subject is explicitly robo investing
- The supplied description connects automation with long-term wealth-building
- Presented as a concise book format
- A narrower focus may suit readers who do not want a broad FinTech overview
Cons:- No details confirm how thoroughly it explains robo-advisor accounts
- No description or review details establish the book’s scope or approach
Best for: Readers seeking a direct, concise-format introduction to robo investing before researching specific account providers.
Not ideal for: Investors who need verified, detailed guidance on provider features, fees, portfolio construction, or account setup.
- Product type:Book
- Format:Book; specific format not supplied
- Stated subject:Robo investing
- Stated focus:Automated investment strategies
- Account service:Not an investment account
- Length:Not specified
- Publication details:Not supplied
- ASIN:1394225229
Our verdict“I’d pick it for a direct, approachable introduction, but not as a standalone guide to selecting a real robo-advisor account.”
Using AI for Personal Finance: Budget Bots and Investment Advisors (AI in Everything Everywhere)
Using AI for Personal Finance stands out for connecting budgeting tools with investment advisors. A robo-advisor account is only one part of a person’s financial picture; cash flow, saving habits, and investing goals can shape how someone uses automated management. The supplied description explicitly covers AI applications in both budgeting and investing, making this a broader personal-finance angle than The Little Book of Robo Investing.
The tradeoff is that the description does not clarify how much attention the book gives to investment accounts specifically. It may be useful for readers curious about AI across everyday money tasks, but I cannot confirm whether it explains portfolio design, advisory fees, tax features, or how to compare providers. FinTech Innovation is a stronger choice if the priority is an explicit discussion of robo-advisors alongside goal-based investing; this title is more appealing when budgeting and investing belong in the same learning path.
There are also no supplied details on format, length, examples, or the book’s level. I would treat it as an introductory topic resource, not a recommendation to rely on an AI tool for financial decisions. Skip it if your immediate goal is a provider shortlist or a detailed account-opening walkthrough, since those elements are not documented.
Pros:- Covers AI applications in budgeting and investing
- Keeps the discussion within personal finance
- Connects day-to-day money management with investment-advisor tools
- Offers a broader personal-finance angle than the robo-investing-specific title
Cons:- No supplied details establish how much content addresses robo-advisor accounts
- Format, length, examples, and technical depth are not provided
- No provider, fee, or portfolio comparisons are confirmed
Best for: Readers who want to explore AI’s role across personal budgeting and investment-advisor tools, rather than investing alone.
Not ideal for: Buyers who need confirmed, detailed comparisons of robo-advisor accounts or a practical provider-selection checklist.
- Product type:Book
- Series:AI in Everything Everywhere
- Named topic:AI for personal finance
- Named topic:Budgeting tools
- Named topic:Investment advisors
- Account service:Not an investment account
- Format and length:Not specified in supplied details
- ASIN:B0FR2J848G
Our verdict“I recommend it for readers interested in the link between AI budgeting and investing, while ranking it below the titles with clearer robo-advisor coverage.”
Fire the Fees: Be Your Own Financial Advisor — Build a Professional Investment Plan with AI
Fire the Fees is aimed at everyday investors who want to build an investment plan independently, with AI as part of the process. That makes it the most DIY-oriented title in this group. Compared with Using AI for Personal Finance, which spans budgeting and investing, this book’s title points more directly toward plan construction. Compared with FinTech Innovation, its apparent focus is personal action rather than the wider development of financial technology.
That positioning may appeal to readers who want a framework for thinking about their own investments, but the supplied details are especially limited: there is no description beyond the title and no confirmation of methods, safeguards, examples, or the book’s intended level. The phrase “fire the fees” is a title, not proof that self-directed investing is suitable for every reader or that AI can replace regulated advice. A plan still needs to reflect goals, time horizon, risk capacity, taxes, and the investor’s willingness to manage decisions.
I would use this as a possible prompt for independent research, not as evidence that AI-generated guidance is dependable. Readers who want a confirmed overview of robo-advisor concepts are better served by FinTech Innovation or The Little Book of Robo Investing, whose supplied descriptions state their subject matter more clearly. Skip this one if you expect documented account comparisons or verified planning tools.
Pros:- Targets everyday investors
- The title explicitly focuses on building an investment plan
- Presents a DIY approach rather than managed-account selection
- Raises the topic of AI-assisted planning
Cons:- No substantive product description is supplied
- The methods, examples, and safeguards are not confirmed
- No direct robo-advisor account comparison is documented
Best for: Self-directed investors curious about using AI while organizing a personal investment plan.
Not ideal for: Readers who need a verified guide to robo-advisor providers, regulatory protections, or the limitations of AI-generated financial guidance.
- Product type:Book, inferred from title and supplied description
- Stated audience:Everyday investors
- Stated focus:Building an investment plan
- Named approach:AI-assisted planning
- Account service:Not an investment account
- Methods and examples:Not specified in supplied details
- Format and length:Not specified
- ASIN:B0H9HS7HYS
Our verdict“I’d consider it for a DIY planning perspective, but its sparse supplied information keeps it behind books with confirmed robo-advisor subject coverage.”
AI, FinTech, and the Future of Robo-Advisory: Risk Management and Ethical Considerations
AI, FinTech, and the Future of Robo-Advisory takes the most specialized angle in this lineup: its supplied description names risk management and ethical considerations. Those subjects matter when evaluating automated advice because portfolio recommendations, data use, and decision processes can affect investors in ways that are not obvious from an account’s interface. This perspective differs from FinTech Innovation, which has broader confirmed coverage of robo-advisors, goal-based investing, and gamification.
The specialization is also the limitation. The provided details do not say whether the book is written for everyday investors, finance students, or industry professionals, and they do not confirm practical account-selection advice. Its designation in the Contributions to Finance and Accounting series suggests a finance-and-accounting context, but I cannot infer its reading level or usefulness for a consumer from the series name alone. The description also gives no specifics about examples, methods, or the treatment of current AI systems.
I would choose this title after a general introduction if I want to examine risks and ethics around robo-advisory. For a first pass at understanding account concepts, The Little Book of Robo Investing appears more direct, while the first-place FinTech title covers more named themes. Skip this one if your main need is a plain-language checklist for choosing a provider or opening an account.
Pros:- Explicitly addresses AI and FinTech in robo-advisory
- Names risk management as a focus
- Includes ethical considerations
- Provides a distinct specialized angle compared with broader introductory titles
Cons:- No description details establish its audience or reading level
- Practical account-selection content is not confirmed
- No information is supplied about examples, length, or methods
Best for: Readers interested in risk management and ethical questions surrounding AI-enabled robo-advisory.
Not ideal for: Beginners looking for a confirmed plain-language account guide, provider comparison, or step-by-step investment setup.
- Product type:Book
- Series:Contributions to Finance and Accounting
- Named topic:AI and FinTech
- Named subject:Robo-advisory
- Stated focus:Risk management
- Stated focus:Ethical considerations
- Account service:Not an investment account
- ASIN:B0H98LDKHP
Our verdict“I’d choose it for a focused risk-and-ethics perspective, but not as my first resource for comparing robo-advisor accounts.”
How We Picked
I ranked these products by how clearly their supplied descriptions help a reader understand robo-advisor investment accounts, not by pretending they are account providers. The first filter was relevance: does the available product information explicitly discuss robo-advisors or robo investing? Next, I considered whether a title adds useful decision themes—such as goal-based investing, AI-assisted planning, risk management, or ethical concerns—that can help a reader form better questions for providers.
Specificity matters more than a broad title promise. FinTech Innovation ranks first because its description names robo-advisors and goal-based investing, giving readers several concrete subjects to explore. The Little Book of Robo Investing ranks second for directness and its stated concise format, although details on its coverage are missing. The AI personal finance book and Fire the Fees are relevant to AI and investing but have limited supplied information about their contents. AI, FinTech, and the Future of Robo-Advisory offers a distinct risk-and-ethics angle, but its description provides little information about practical account selection.
I did not infer publication quality, author expertise, performance claims, or the quality of any investment recommendations from titles alone. The provided information does not include enough detail to evaluate length, format, examples, or whether the material is current for 2027. Since none of these products is an account, I also did not rank them by fees, investment minimums, portfolio options, or service quality. My ranking is a guide to choosing a learning resource before comparing real robo-advisor providers.
| robo advisor investment account | Product type | Series | Format and length | Stated focus |
|---|---|---|---|---|
| FinTech Innovation: From Robo- | Book | The Wiley Finance Series | Not specified in supplied details | — |
| The Little Book of Robo Invest | Book | — | — | Automated investment strategies |
| Using AI for Personal Finance: | Book | AI in Everything Everywhere | Not specified in supplied details | — |
| Fire the Fees: Be Your Own Fin | Book, inferred from title and supplied description | — | Not specified | Building an investment plan |
| AI | Book | Contributions to Finance and Accounting | — | Risk management |
Factors to Consider When Choosing Robo Advisor Investment Accounts
These books can help shape your research, but choosing a robo-advisor investment account requires comparing actual providers. I’d separate educational material from account features: a book can explain a concept, while a provider’s current disclosures describe what its service offers and what it charges.
Start with the service you actually need
A robo-advisor typically uses information about an investor’s goals and risk tolerance to recommend or manage a portfolio, but services differ. Some provide automated portfolio management with little human contact; others offer access to human financial professionals or broader planning. Before looking at account names, I’d decide whether I need investment management alone, help setting goals, or ongoing access to a person. The books here do not establish which providers offer those services, so I would verify each feature on provider materials.
Match the service to the task. If I mainly want a diversified portfolio managed according to a chosen risk level, a straightforward automated account may suit me. If I need help with a complicated tax situation, business finances, or coordinated retirement decisions, I would check whether a provider’s human support is adequate or seek independent professional advice. A book about AI or FinTech should not be mistaken for evidence that a particular account meets those needs.
Compare total fees, not a single headline
Account costs can include an advisory fee, fund expense ratios, and charges tied to particular services or transactions. I’d check the provider’s current fee schedule and determine what applies to the account balance and the portfolio it recommends. Two providers can describe their services in similar terms while differing in the cost of underlying investments or access to additional advice. The supplied product information for these books contains no provider-fee data, so I would not use any of them to settle this comparison.
Ask what the fee covers, whether it changes with account size, and whether add-on services carry separate charges. Also check whether cash allocations affect how much of the account is invested and how that cash is handled. Cost matters over time, but the cheapest service is not automatically the right fit if its support, tools, or investment approach do not match your needs.
Look at portfolio design and risk controls
Providers may differ in the investments they use, how they set a portfolio, how often they rebalance, and whether they offer options such as socially responsible portfolios or tax-sensitive management. I’d read the portfolio methodology and ask how the service responds when markets move or a user’s goals change. A risk questionnaire can guide a recommendation, but it does not remove investment risk or guarantee a portfolio will suit every personal circumstance.
Risk management is a useful reading lens for the title focused on AI, FinTech, and robo-advisory, but a book’s subject is not proof of a provider’s safeguards. For an account, look at the actual investment policy, available asset choices, rebalancing rules, and explanations of potential losses. I would also check whether the provider allows a user to adjust assumptions or request help if a recommended portfolio feels unsuitable.
Check account types, taxes, and withdrawal rules
Many investors need to choose between taxable and tax-advantaged accounts, and the rules can affect contributions, withdrawals, and tax reporting. I’d confirm which account types a provider supports and whether its tax-related tools apply to my situation. Features such as tax-loss harvesting may have eligibility requirements and do not guarantee a tax benefit. I would not assume that an account’s automated service handles every tax decision or replaces advice from a tax professional.
Before transferring assets, check how the provider handles existing investments, cash, and account closure. Find out whether moving securities in kind is possible or whether holdings may need to be sold, since a sale can have tax consequences in a taxable account. Read transfer and withdrawal rules directly; none of the five books is documented as offering current provider-specific instructions.
Decide how much human support you want
Some investors are comfortable with an app, automated messages, and self-service answers; others want a person available for planning questions. Support can differ by channel, availability, and the type of advice offered. I’d ask whether human assistance is included, whether it is limited to account questions, and whether the professional can address broader financial planning. A product title about AI-assisted investing does not tell me how much human support a real account provides.
Service fit is personal. If I am new to investing, access to clear explanations and timely help may matter as much as the portfolio interface. If I already have a defined plan and need routine management, a more automated service could be enough. The best account is not necessarily the one with the most automation; it is the one whose level of guidance matches the decisions I want to handle myself.
Use books as context, then verify current details
The lineup offers different learning angles: FinTech Innovation covers robo-advisors, goals, and gamification; The Little Book of Robo Investing is described as a concise introduction; and the AI-focused books widen the discussion to budgeting, DIY planning, or risk and ethics. That makes them research companions, not account substitutes. The supplied information does not confirm publication currency, detailed provider examples, or the depth of each book’s guidance.
After reading, I’d build a comparison sheet with the account’s fees, minimum balance, account types, investment choices, tax features, support options, and withdrawal rules. I would verify each item against current provider documents and ask questions before transferring money. If a book or automated tool makes a performance promise, I would treat that as a reason to seek stronger evidence rather than a guarantee of future results.
Frequently Asked Questions
Are any of these products robo-advisor investment accounts?
No. All five products supplied for this guide are books, not financial accounts or investment-management services. They cover topics related to robo-advisors, AI, personal finance, or investment planning, but they cannot hold assets or manage a portfolio. To open an account, I would compare actual providers and review their current service terms, fees, investment approach, and account disclosures.
Which book is the strongest starting point for learning about robo-advisors?
FinTech Innovation: From Robo-Advisors to Goal-Based Investing and Gamification is my first pick for broad coverage because its supplied description explicitly names robo-advisors and goal-based investing. Readers wanting a more direct, concise-format introduction may prefer The Little Book of Robo Investing. Neither product’s supplied details confirm a current provider comparison or a step-by-step account-opening guide.
Can I use one of these books to choose an account’s fees or portfolio?
The supplied product information does not establish that any book contains current provider fee tables or detailed portfolio comparisons. I would use the books to develop questions, then check each provider’s current fee schedule, investment methodology, fund costs, and account terms. Features and charges can change, so account decisions should rely on up-to-date provider documents rather than a general book description.
Is AI-generated investment guidance a replacement for a robo-advisor or financial professional?
No. A book about AI-assisted planning does not establish that an AI tool provides reliable, personalized, or regulated financial advice. A robo-advisor account is a service with its own investment process and disclosures, while a human professional may offer guidance suited to a person’s broader financial circumstances. I would check what a tool or provider actually does, understand its limits, and seek qualified professional help when my situation calls for it.
What should I compare before opening a robo-advisor account?
I would compare advisory and fund fees, account minimums, portfolio options, rebalancing practices, tax-related features, supported account types, human support, and transfer or withdrawal rules. I’d also consider how much control I want and whether the service’s risk process reflects my goals and time horizon. These five books do not provide confirmed account-level specifications, so I would verify each point directly with the providers under consideration.
Conclusion
For a broad introduction to robo-advisors and investing technology, I’d start with FinTech Innovation. If I wanted a more direct, concise-format overview, I’d choose The Little Book of Robo Investing. Readers interested in the connection between budgeting and investing may prefer Using AI for Personal Finance; DIY investors curious about AI-supported planning can investigate Fire the Fees; and readers focused on risk and ethics may find AI, FinTech, and the Future of Robo-Advisory the most relevant. Each recommendation is for learning, not account management.
Before opening an account, I would compare real providers on costs, portfolio design, account types, taxes, support, and withdrawal terms. The supplied information for these five books does not confirm current account details, so the final decision should come from current provider disclosures and, where needed, qualified financial guidance.
Halloween Picks

Vexalify 11-Inch Halloween Pumpkin Fog Machine with 12-Color Lights

Thuodo 8 FT Tall Halloween Inflatable Three-Headed Dragon with LEDs

Max Fun 10-Foot Halloween Dragon and Pumpkin Inflatable Archway with LED Lights
As an affiliate, we earn on qualifying purchases.