Credit card debt payoff planners turn a vague goal into a visible, trackable plan, and the differences between them matter more than you might expect. The Debt Payoff Blueprint: A 90-Day Step-by-Step Plan earns my top spot because it pairs tracking pages with an actual repayment strategy, not just blank charts. If you want a guided beginner experience, the Debt Payoff Made Simple Planner: 90-Day Credit Card and Loan Tracker is easier to follow, while the 3-Pack Debt Payoff Planner delivers the best value for households tracking multiple debts across family members. The core tradeoff in this category is between structured, method-driven workbooks that teach a strategy and simple tracker notebooks that log payments without telling you what to pay first. Spiral binding, page count, and whether the planner supports snowball versus avalanche methods also separate the winners from the filler. Read on for the full breakdown of all 14 options.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
Key Takeaways
- Only three planners in this lineup (the Blueprint, the Made Simple Planner, and the Comprehensive Guide) include an actual repayment methodology — the other eleven are payment trackers that assume you already know your strategy.
- The 3-Pack stood out as the only multi-unit option, making it the clear value pick for couples or anyone juggling separate debt payoff plans for credit cards, student loans, and car payments.
- Spiral binding appeared on the three most durable options; perfect-bound planners cost less but rarely survive daily desk use for a full 90-day payoff sprint.
- 90-day formats dominated this roundup, which favors short, aggressive payoff sprints — buyers with large balances should look for the longer Monthly Tracker instead.
- Several near-identical tracker notebooks fill this category, differing mainly in sheet count (53 sheets versus 120 pages) and visual payoff charts, so page layout matters more than brand name here.
| Debt Payoff Planner: Debt and Credit Card Tracker |  | Best for a Simple Starting Point | Product type: Debt payoff planner | Stated tracking focus: Debts and credit card balances | Purpose: Organizing debt payoff progress and finances | VIEW LATEST PRICE | See Our Full Breakdown |
| 3-Pack Debt Payoff Planner, 8.5×11 Inch, 120 Pages Spiral Bound |  | Best for Multiple Budgets or Long-Term Tracking | Quantity: 3 planners | Page count: 120 pages each (60 double-sided sheets) | Size: 8.5 x 11 inches | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner – Spiral Bound 8.5×11 Inch Debt & Bill Payment Tracker Notebook |  | Best for Detailed Household Tracking | Size: 8.5 x 11 inches | Page count: 110 pages | Paper: 80 gsm, double-sided printing | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner and Credit Card Debt Tracker | 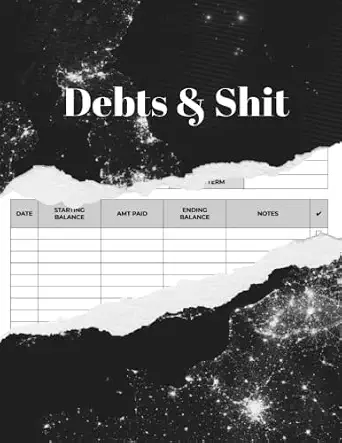 | Best for One-Creditor-at-a-Time Planning | Page count: 111 pages | Tracking capacity: 1 creditor per page | Stated tracking focus: Debt payoff and credit card debt | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner: A Comprehensive Guide to Eliminate Debt, Manage Credit Cards, and Take Control of Your Finances |  | Best for Buyers Seeking Guidance Alongside Tracking | Format: 8.5 x 11 inches | Pages: 140 | Type: Debt payment tracker and planner | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Snowball Tracker: A Debt Reduction Planner |  | Best for the Snowball Method | Product type: Debt reduction planner notebook | Strategy: Debt snowball (smallest balance first) | Primary focus: Debt repayment tracking and motivation | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner: Debt Payment Tracker |  | Best Straightforward Logbook | Product type: Debt payment tracker planner | Pages: 105 | Size: 8.5 x 11 inches | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Made Simple Planner: 90-Day Credit Card and Loan Tracker |  | Best for a 90-Day Debt Sprint | Product type: 90-day debt payoff planner | Tracking period: 90 days | Tracks: Credit card and loan balances, payments, and financial progress | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner: Debt Tracker for Credit Cards and Loans |  | Best Capacity for Multi-Debt Households | Product type: Debt payoff planner | Dimensions: 8.5 x 11 inches | Page count: 100+ pages | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Blueprint: A 90-Day Step-by-Step Plan to Pay Off Credit Card Debt |  | Best Educational Strategy Guide | Format: Book | Program length: 90 days | Structure: Step-by-step daily plan | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner – 8.5″ x 11″ Financial Tracker Notebook, 53 Sheets |  | Best for Detailed Payment Logging | Product Type: Debt Payoff Planner | Size: 8.5″ x 11″ | Sheet Count: 53 sheets | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner: Credit Card and Loan Balance Tracker |  | Best for Combined Card and Loan Tracking | Product Type: Debt payoff planner | Debt Types Covered: Credit cards and loans | Primary Function: Balance tracking toward payoff | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner: Debt Payment Tracker |  | Best Long-Haul Capacity | Product Type: Debt payoff planner | Size: 8.5 x 11 inches | Pages: 100+ | VIEW LATEST PRICE | See Our Full Breakdown |
| Debt Payoff Planner: Monthly Tracker for Paying Off Your Debts |  | Best for the Debt Snowball Method | Type: Debt payoff planner / tracker | Method: Debt snowball | Format: Monthly tracker | VIEW LATEST PRICE | See Our Full Breakdown |
| credit card debt payoff planner | Product type | Format |
|---|---|---|
| Debt Payoff Planner: Debt and | Debt payoff planner | Not specified |
| 3-Pack Debt Payoff Planner | — | — |
| Debt Payoff Planner | — | — |
| Debt Payoff Planner and Credit | — | Journal |
| Debt Payoff Planner: A Compreh | — | 8.5 x 11 inches |
| Debt Snowball Tracker: A Debt | Debt reduction planner notebook | Physical notebook |
| Debt Payoff Planner: Debt Paym | Debt payment tracker planner | — |
| Debt Payoff Made Simple Planne | 90-day debt payoff planner | Not specified |
| Debt Payoff Planner: Debt Trac | Debt payoff planner | — |
| Debt Payoff Blueprint: A 90-Da | — | Book |
| Debt Payoff Planner | Debt Payoff Planner | — |
| Debt Payoff Planner: Credit Ca | Debt payoff planner | Physical planner |
| Debt Payoff Planner: Debt Paym | Debt payoff planner | — |
| Debt Payoff Planner: Monthly T | — | Monthly tracker |
More Details on Our Top Picks
Debt Payoff Planner: Debt and Credit Card Tracker
A focused debt and card tracker makes this a straightforward pick for someone who wants a paper place to record balances and follow payoff progress. Its description stays broad, though: unlike the 3-Pack Debt Payoff Planner, it does not specify fields for interest rates, payments, or creditor notes, so I can’t tell how much detail each entry supports. That gap matters if you’re comparing APRs or coordinating payments across several cards. On the other hand, buyers who only need a basic record may prefer its uncluttered premise to a notebook that also serves as an expense ledger. The limited product information makes this a less certain fit than the more fully specified planners here, but its stated purpose is tightly aligned with tracking credit card debt.
Pros:- Explicitly focused on debt and credit card balances
- Provides a place to organize payoff progress
- Simple stated purpose may suit buyers who want a basic tracker
Cons:- Layout and specific tracking fields are not described
- No page count, dimensions, or binding details are provided
- Unclear whether it supports comparing interest rates or recording payment history
Best for: Someone starting a paper record of a few card balances who wants a planner explicitly focused on debt payoff progress
Not ideal for: Buyers who need confirmed fields for APRs, payment dates, or detailed creditor-by-creditor planning
- Product type:Debt payoff planner
- Stated tracking focus:Debts and credit card balances
- Purpose:Organizing debt payoff progress and finances
- Format:Not specified
- Page count:Not specified
- Binding:Not specified
Our verdict“Choose this if you want a plainly described debt and card tracker and can accept uncertainty about its layout and tracking fields.”
3-Pack Debt Payoff Planner, 8.5×11 Inch, 120 Pages Spiral Bound
Three full-size notebooks give this set a distinct advantage for households tracking separate budgets, or for anyone who wants a fresh book for different payoff periods. Each planner has 120 pages and named fields for creditors, balances, interest rates, payments, and notes, so it offers more confirmed detail than Debt Payoff Planner: Debt and Credit Card Tracker. The monthly expense and bill payment use also gives it broader utility than the single-creditor-per-page Debt Payoff Planner and Credit Card Debt Tracker. The tradeoff is a fully manual routine: balances and payments must be entered by hand, and three large 8.5 by 11 inch books take storage space. I’d favor this set when writing room and a defined tracking structure matter more than portability or digital calculations.
Pros:- Set includes three planners for separating budgets or payoff periods
- Named fields cover creditors, balances, interest rates, payments, and notes
- Monthly expense and bill payment tracking extends its use beyond debt records
- Spiral binding is described as laying flat for writing
Cons:- Manual entries take ongoing time and do not calculate payoff progress automatically
- 8.5 by 11 inch books are less portable than compact trackers
- The product description provides no independent evidence about paper or binding durability
Best for: Households or organized borrowers who want separate paper trackers for multiple budgets, people, or payoff periods
Not ideal for: Traveling users or anyone who wants automatic balance updates, payoff calculations, or a compact notebook
- Quantity:3 planners
- Page count:120 pages each (60 double-sided sheets)
- Size:8.5 x 11 inches
- Binding:Spiral bound
- Cover:350 gsm kraft paper
- Paper weight:80 gsm
- Listed tracking fields:Creditors, balances, interest rates, payments, and notes
- Additional stated use:Monthly expense and bill payment tracking
Our verdict“Pick this set if you want generous writing space and detailed manual tracking across more than one budget or payoff period.”
Debt Payoff Planner – Spiral Bound 8.5×11 Inch Debt & Bill Payment Tracker Notebook
Detailed tables on double-sided paper make this a practical fit for borrowers who want debt records and bill payments together in one notebook. Its listed fields cover creditors, balances, payments, interest rates, and payoff goals, a more explicit setup than Debt Payoff Planner: Debt and Credit Card Tracker. Compared with the 3-Pack Debt Payoff Planner, this option provides one book rather than separate copies, but its description adds a specific emphasis on payoff goals and family or small-business use. The spiral binding lays flat at 180 degrees, which helps when writing across a large page. That size also limits portability, and every balance still needs manual entry. Choose it for structured, shared tracking; skip it if you need a pocketable tool or automatic calculations.
Pros:- Tables specify creditors, balances, payments, interest rates, and payoff goals
- Spiral binding is described as opening flat at 180 degrees
- Double-sided 80 gsm pages support a substantial tracking notebook
- The stated use includes personal, family, and small-business planning
Cons:- Large 8.5 by 11 inch format is less convenient to carry
- Manual tracking requires users to update balances and payments themselves
- Unlike the three-book set, it does not provide separate notebooks for multiple budgets
Best for: Families or small-business owners who want a large, structured paper ledger for creditors, interest, payments, and goals
Not ideal for: Borrowers who need a portable planner or want debt balances and payoff targets calculated automatically
- Size:8.5 x 11 inches
- Page count:110 pages
- Paper:80 gsm, double-sided printing
- Binding:Spiral bound; lays flat at 180 degrees
- Cover:Copperplate
- Color:Black
- Material:Paper
- Listed tracking fields:Creditors, balances, payments, interest rates, and payoff goals
Our verdict“Choose this single large ledger if you want defined debt and bill tracking fields for a household or small business.”
Debt Payoff Planner and Credit Card Debt Tracker
One creditor per page gives this journal a simple organizing rule: each card or lender gets its own space, so balances are less likely to blur together. That format is more clearly defined than Debt Payoff Planner: Debt and Credit Card Tracker, whose layout is not specified. It may also suit a borrower who finds the broad tables in the 3-Pack Debt Payoff Planner excessive. The constraint is just as clear: a separate page for every creditor can use space quickly for someone with several accounts, and the description does not say whether the page includes fields for interest rates, payment dates, or payoff goals. With 111 pages listed, this is a focused journal rather than a confirmed full budget system. I’d choose it for uncomplicated account-by-account organization, not detailed APR comparisons.
Pros:- Dedicated page for each creditor separates account records
- Designed to organize debt payoff plans
- Explicitly includes credit card debt tracking
- Page count is specified
Cons:- One creditor per page can use pages quickly for borrowers with many accounts
- Specific fields on each page are not described
- No dimensions, paper, or binding details are provided
Best for: A borrower with a small number of cards or loans who prefers to keep each creditor’s record on its own page
Not ideal for: People managing many accounts or needing confirmed APR, payment schedule, and payoff goal fields
- Page count:111 pages
- Tracking capacity:1 creditor per page
- Stated tracking focus:Debt payoff and credit card debt
- Format:Journal
- Dimensions:Not specified
- Binding:Not specified
Our verdict“Pick this journal if keeping each creditor on a separate page is your main organizing need and you have a manageable number of accounts.”
Debt Payoff Planner: A Comprehensive Guide to Eliminate Debt, Manage Credit Cards, and Take Control of Your Finances
Guidance paired with a debt payment tracker is the stated draw here, making this a different choice from notebooks described mainly through their tables and binding. At 140 pages, it offers more listed pages than the 110-page spiral planner, although page count alone does not show how much space is devoted to instruction versus writing. The large 8.5 by 11 inch format matches the roomy planners in this group, while its description names credit card management and debt elimination as central themes. Compared with the 3-Pack Debt Payoff Planner, it is presented as a guide rather than a set of detailed ledgers, and the available information does not specify fields for APRs, payments, or creditor notes. It makes the most sense for readers who want guidance in a paper format; buyers seeking proven tabular tracking should choose a more fully specified notebook.
Pros:- Description pairs debt elimination guidance with debt payment tracking
- 140 pages provide substantial room for a planner or guide
- Large format offers more writing area than a compact notebook
- Credit card management is an explicit focus
Cons:- The split between guidance and tracking space is not specified
- No individual fields or page layout are described
- Physical format does not suit borrowers who prefer digital budgeting tools
Best for: A self-directed borrower who wants written guidance on debt elimination alongside a paper credit card debt planner
Not ideal for: Users who need confirmed creditor-by-creditor fields, a specified layout, or a digital tracker
- Format:8.5 x 11 inches
- Pages:140
- Type:Debt payment tracker and planner
- Stated guidance focus:Eliminating debt
- Stated management focus:Credit cards
- Tracking detail:Debt payment tracking; specific fields not stated
Our verdict“Choose this if you want a large paper guide and tracker in one product and do not need a confirmed detailed ledger layout.”
Debt Snowball Tracker: A Debt Reduction Planner
Most payoff planners on this list are strategy-agnostic — they give you grids and let you decide how to attack your balances. This one is different because it is built entirely around the debt snowball method, where you pay off the smallest balance first and roll that payment into the next debt. That structure matters: the snowball works best when the tracker reinforces it, and this planner sequences your debts and celebrates each payoff in the right order. Compared with the Debt Payoff Planner: Debt Payment Tracker, which simply records payments, this option nudges you toward a proven psychological framework. The tradeoff is flexibility — if you prefer the avalanche method (highest interest first), much of the built-in logic works against you, and the thin product documentation means you’re buying on method alone.
Pros:- Purpose-built for the debt snowball strategy
- Sequenced payoff structure keeps motivation high
- Turns tracking into a method rather than just a logbook
- Simple focus on debt reduction without clutter
Cons:- No published page count or dimensions, so size and longevity are unknown
- Locked into one strategy — poor fit for avalanche planners
- Sparse product details make it hard to evaluate layout before buying
Best for: Beginners who want motivation from quick wins and are committed to the smallest-balance-first approach
Not ideal for: Math-driven borrowers who prefer the avalanche method — the snowball structure will feel like the wrong tool
- Product type:Debt reduction planner notebook
- Strategy:Debt snowball (smallest balance first)
- Primary focus:Debt repayment tracking and motivation
- Tracks:Multiple debts in payoff order
- Format:Physical notebook
- Page count:Not specified
- Dimensions:Not specified
Our verdict“Choose this if you know the snowball method works for your motivation style and want a tracker that enforces it.”
Debt Payoff Planner: Debt Payment Tracker
Where the Debt Snowball Tracker commits to one repayment philosophy, this planner stays neutral and does one job well: recording payments. With 105 pages in a full 8.5 x 11-inch format, it matches the generous dimensions of the Debt Payoff Planner: Debt Tracker for Credit Cards and Loans while positioning itself as a pure credit-card-focused log. That neutrality is its strength for anyone who already has a strategy and just needs a disciplined place to write things down. The flip side is that there is no visible guidance layer — unlike the Debt Payoff Blueprint, which teaches a 90-day plan, this assumes you know what you’re doing. Buyers who want education bundled with tracking will find it bare, and the lack of interior-layout details means you can’t verify the grid design before it arrives.
Pros:- Strategy-neutral, so it works with any repayment approach
- 105 pages gives long runway for multi-year payoffs
- Full 8.5 x 11-inch pages offer ample writing space
- Dedicated focus on credit card balances keeps things simple
Cons:- No educational content or structured plan included
- Interior layout details not disclosed, so format is a gamble
- No timeline structure — easy to lose momentum without one
Best for: Self-directed borrowers who already have a payoff strategy and want a no-frills, large-format payment log
Not ideal for: First-timers who need instructions, coaching, or a built-in method — this is a blank-ledger experience
- Product type:Debt payment tracker planner
- Pages:105
- Size:8.5 x 11 inches
- Primary focus:Credit card balances and debt payoff
- Strategy:None prescribed — neutral logbook
- Educational content:No
Our verdict“A solid pick if you treat a planner as a record-keeping tool rather than a coach, and you value page capacity over guidance.”
Debt Payoff Made Simple Planner: 90-Day Credit Card and Loan Tracker
This planner’s defining feature is its 90-day tracking window, which reframes debt payoff as a series of short sprints rather than an open-ended grind. That’s a genuinely different proposition from the Debt Payoff Planner: Debt Payment Tracker, whose 105 open-ended pages can quietly encourage drifting. A defined endpoint creates urgency, and tracking both credit cards and loans in one place makes it more versatile than credit-card-only options. It shares the 90-day concept with the Debt Payoff Blueprint, but where that book is primarily instructional, this is primarily a tracker — you get the workbook habit without the reading assignment. The drawback cuts both ways: for debts that will take years to clear, a 90-day horizon means buying replacement planners repeatedly, and the total absence of format details leaves real uncertainty about page size and layout quality.
Pros:- Defined 90-day sprint creates urgency and accountability
- Tracks credit cards and loans in a single planner
- Includes payment and overall financial progress tracking
- Sprint structure pairs well with milestone rewards
Cons:- Short window means repurchasing for long payoff timelines
- No format, size, or layout details available
- Less suited to slow, steady minimum-payment journeys
Best for: Momentum-driven borrowers who want a short, urgent deadline and need to juggle credit cards and loans together
Not ideal for: Anyone with large multi-year balances — the 90-day cycle becomes a recurring expense and resets motivation each quarter
- Product type:90-day debt payoff planner
- Tracking period:90 days
- Tracks:Credit card and loan balances, payments, and financial progress
- Debt types covered:Credit cards and loans
- Format:Not specified
- Structure:Time-boxed sprint format
Our verdict“The right choice if a hard 90-day deadline is the motivation hack you need — just expect to buy the next one at day 91.”
Debt Payoff Planner: Debt Tracker for Credit Cards and Loans
Among the blank-style trackers in this roundup, this one’s appeal is sheer capacity: more than 100 pages in a large 8.5 x 11-inch format, with room to track credit cards and other debts side by side. If your situation involves five cards, a car loan, and a student loan, the generous page size matters more than it sounds — cramped 6 x 9-inch trackers force abbreviations and messy corrections. It competes directly with the Debt Payoff Planner: Debt Payment Tracker (105 pages, same dimensions), and the two are near-peers; this one edges ahead for households whose debt list is long enough to consume page after page. What you give up is any structured timeline — unlike the Debt Payoff Made Simple Planner, there is no sprint clock, so self-discipline has to come entirely from you. It’s a marathoner’s notebook, not a sprinter’s.
Pros:- 100+ pages suit long, multi-year payoff journeys
- Large 8.5 x 11-inch format keeps multi-debt entries readable
- Handles credit cards and other debt types together
- Ample capacity reduces the need to buy replacements
Cons:- No built-in timeline, milestones, or motivational structure
- Volume alone doesn’t help if you lack a repayment method
- Undated pages can let gaps in tracking go unnoticed
Best for: Households juggling many cards and loans who need maximum page space and long-haul capacity
Not ideal for: Borrowers who rely on external structure or deadlines — with no timeline built in, this rewards only the self-disciplined
- Product type:Debt payoff planner
- Dimensions:8.5 x 11 inches
- Page count:100+ pages
- Tracks:Credit cards and other debts
- Strategy:None prescribed — open-ended tracker
- Timeline structure:No
Our verdict“If your debt list is long and your discipline is self-generated, this high-capacity format beats every smaller tracker here.”
Debt Payoff Blueprint: A 90-Day Step-by-Step Plan to Pay Off Credit Card Debt
Every other product in this batch is a tracker — a place to write numbers down. The Debt Payoff Blueprint is the outlier because it’s a book built around instruction: a 90-day, step-by-step plan that tells you what to do, not just where to record it. Its three stated focus areas — clearing up payment-date confusion, lowering credit utilization quickly, and improving your credit score — address outcomes no blank tracker touches. Someone paralyzed by where to start will get more from this than from the Debt Payoff Planner: Debt Payment Tracker, which assumes you already have a plan. It shares the 90-day window with the Debt Payoff Made Simple Planner, but the emphasis is reversed: guidance first, writing space second. The real tradeoff is that structured programs demand commitment — a rigid day-by-day plan can feel punishing if your income is irregular, and there’s minimal dedicated space for ongoing multi-debt logging.
Pros:- Step-by-step 90-day structure removes guesswork for beginners
- Directly targets credit utilization and score improvement
- Simplifies payment-date management to avoid missed payments
- Teaches a repeatable method rather than just tracking one
Cons:- A fixed 90-day program can be too rigid for variable incomes
- Minimal tracking space compared with 100+ page planner notebooks
- Effectiveness claims are hard to verify without review content
Best for: Credit card borrowers who feel stuck at step one and want a prescribed daily plan plus credit score wins
Not ideal for: Experienced budgeters who just need a logbook — the instructional content will feel redundant, and writing space is limited
- Format:Book
- Program length:90 days
- Structure:Step-by-step daily plan
- Primary focus:Credit card debt elimination
- Covers:Payment-date management, credit utilization, credit score improvement
- Educational content:Yes — instructional guide
Our verdict“Pick this if you need to be told exactly what to do each day — skip it if you only need somewhere to write.”
Debt Payoff Planner – 8.5″ x 11″ Financial Tracker Notebook, 53 Sheets
This planner stands out for its record-keeping depth — it’s the only entry in this batch with dedicated space for confirmation numbers, which matters if you’ve ever had a payment dispute and couldn’t prove you paid. The full-letter layout gives room for balances, due dates, interest rates, and recurring bills in one place. Compared with the Debt Payoff Planner: Monthly Tracker, which focuses on snowball strategy, this one is built for the person who wants a paper audit trail alongside a payoff plan. The tradeoff is capacity: 53 sheets runs thin if you’re juggling many debts over multiple years, where the 100+ page Debt Payment Tracker offers more runway. This pick makes the most sense for detail-oriented trackers rather than big-picture planners.
Pros:- Dedicated space for confirmation numbers creates a verifiable payment record
- Covers balances, due dates, and interest rates in one layout
- Supports debt snowball and other repayment strategies
- Combines bill tracking with debt tracking so nothing falls through the cracks
Cons:- 53-sheet count limits long-term, multi-year use
- Manual format demands consistent upkeep to stay useful
Best for: Detail-oriented debtors who log every payment and want confirmation numbers and due dates documented on paper
Not ideal for: Anyone tracking five-plus debts over a multi-year horizon — 53 sheets won’t last the full journey
- Product Type:Debt Payoff Planner
- Size:8.5″ x 11″
- Sheet Count:53 sheets
- Tracking Fields:Balances, due dates, interest rates, confirmation numbers
- Extra Features:Recurring bill tracking
- Strategy Support:Debt snowball and repayment planning
Our verdict“Choose this if you treat your payoff plan like a checkbook register and want proof of every payment on paper.”
Debt Payoff Planner: Credit Card and Loan Balance Tracker
What separates this planner from the single-purpose options in this roundup is its dual focus on credit cards and loans. Most entries, like the Debt Snowball Tracker, lean toward revolving credit card balances, but real household debt usually mixes in a car loan or personal loan too. If your payoff journey spans both debt types, this layout keeps them in a single tracker instead of forcing you to buy two books or improvise. The honest tradeoff: there’s minimal published detail on the interior structure, so you’re betting on a generic-but-versatile format rather than the clearly documented confirmation-number logging of the 8.5″ x 11″ Financial Tracker Notebook. Buyers who want certainty about page layout before purchasing should weigh that gap carefully.
Pros:- Handles credit cards and loans in a single tracker
- Simplifies multi-debt households down to one notebook
- Straightforward premise with no learning curve
Cons:- Sparse product detail makes interior layout a gamble
- No documented strategy framework like snowball or avalanche
Best for: Households juggling both credit card balances and installment loans who want one tracker for everything
Not ideal for: Buyers who need to know exact page layouts and field structure before committing
- Product Type:Debt payoff planner
- Debt Types Covered:Credit cards and loans
- Primary Function:Balance tracking toward payoff
- Format:Physical planner
Our verdict“A sensible pick if your debt spans cards and loans, but go in knowing the interior layout is undocumented.”
Debt Payoff Planner: Debt Payment Tracker
With 100+ pages at full letter size, this tracker outlasts the 53-sheet Financial Tracker Notebook by roughly double, which is the whole point: if you’re staring down a three-to-five-year payoff timeline, replacing a planner mid-journey breaks your momentum and your historical record. The larger page budget also means less cramped entries when you’re logging multiple payments per month across several cards. Where it falls short compared with the Monthly Tracker for Paying Off Your Debts is guidance — there’s no stated framework or method baked in, so it works best for someone who already knows their strategy and just needs durable space to execute it. Beginners who want structure should look elsewhere in this roundup first.
Pros:- 100+ pages provide multi-year tracking capacity
- Full 8.5 x 11 format keeps entries readable
- Tracks payment history for long-haul motivation
Cons:- No published interior layout details
- No built-in payoff methodology or guidance
Best for: Debtors on multi-year payoff timelines who already have a strategy and need capacity to match
Not ideal for: First-timers who want a built-in method or coaching structure to follow
- Product Type:Debt payoff planner
- Size:8.5 x 11 inches
- Pages:100+
- Intended Use:Track debt payments and organize finances
- Focus:Credit card payoff progress
Our verdict“The volume pick — buy it when your payoff timeline is measured in years, not months.”
Debt Payoff Planner: Monthly Tracker for Paying Off Your Debts
This is the pick for buyers who want method, not just blank pages. Built around the debt snowball — paying off smallest balances first — the monthly structure turns an intimidating total into a sequence of winnable months, which is exactly why the snowball approach works for motivation. Compared with the Credit Card and Loan Balance Tracker, which is format-agnostic, this planner gives you a proven framework and a monthly cadence for reviewing progress. The tradeoffs are real: a monthly tracker demands you actually sit down every month, and there’s little published detail to verify print or paper quality, unlike the fully documented 8.5″ x 11″ Financial Tracker Notebook. For someone who thrives on routine and quick psychological wins, those risks are worth taking.
Pros:- Built around the proven debt snowball method
- Monthly cadence creates a sustainable review habit
- Handles multiple credit card debts in one organized view
- Encourages broader control over personal finances
Cons:- Effectiveness depends entirely on consistent monthly manual effort
- No detailed product description to verify layout or quality
Best for: Motivation-driven debtors who want small-balance wins and a fixed monthly check-in routine
Not ideal for: Anyone allergic to monthly paperwork, or analytical types who’d rather prioritize by interest rate
- Type:Debt payoff planner / tracker
- Method:Debt snowball
- Format:Monthly tracker
- Use:Budgeting and debt management
- Debt Focus:Multiple credit card debts
Our verdict“If quick wins from knocking out small balances keep you going, this monthly snowball tracker fits the bill.”

How We Picked
I evaluated each planner against four buyer-relevant criteria. First, strategic value: does the planner just record payments, or does it explain a payoff method like debt snowball or debt avalanche and help you sequence payments? Second, layout and usability: I looked at page count, payoff progress visualizations, monthly budget integration, and whether the size (8.5×11 versus more compact formats) fits real desk habits. Third, build quality: spiral binding that lies flat beats glued spines for a tool you open daily, and thicker paper handles highlighters and gel pens without bleeding. Fourth, fit for different debt situations — a 90-day sprint format suits aggressive payers, while open-ended monthly trackers serve large balances better.
The ranking logic is straightforward: planners that combine strategy with tracking placed highest because they serve beginners and experienced budgeters alike. Pure tracker notebooks ranked by layout quality, durability, and value, with multi-packs credited for their per-unit cost advantage. Workbooks that were thin, method-light, or duplicated by better-designed competitors landed at the bottom of the list.
Factors to Consider When Choosing Credit Card Debt Payoff Planners
Before choosing a payoff planner, think about how you actually manage money day to day. The right planner matches your debt size, your payoff timeline, and how much guidance you need — buying the wrong format is the most common mistake in this category.Tracker Versus Strategy Workbook
The biggest decision is whether you need a payment log or a repayment coach. Tracker notebooks give you grids to record balances and payments, which works well if you already follow a method and just need accountability. Strategy workbooks explain concepts like the debt snowball (paying smallest balances first for motivation) and the debt avalanche (paying highest-interest cards first for math savings), then walk you through sequencing your payments. Beginners who skip the strategy component often stall out because a tracker shows progress but never tells you where the next dollar should go. If you have never compared snowball and avalanche outcomes on your own balances, a workbook-style planner will pay for itself in avoided interest. Experienced budgeters can safely buy the cheaper tracker options.
Payoff Timeline Format
Most planners in this category are built around a 90-day sprint, and that format is not right for everyone. Short-cycle planners create urgency and frequent win moments, which helps with motivation but assumes you can make meaningful progress in three months. If you carry large balances, a 90-day book will run out long before your debt does, forcing you to buy another copy mid-plan. Open-ended monthly trackers, or planners with 120 pages of repeating payment logs, suit multi-year payoff journeys far better. Match the format to your realistic payoff date, not the one you wish you had — abandoning a planner because it expired early is a common failure point.
Binding and Daily Durability
A payoff planner is a daily-use tool, and binding quality determines whether it survives the journey. Spiral-bound planners lie flat, which matters when you are filling in payment grids at a desk or copying numbers from a banking app. Perfect-bound (glued) books are cheaper and look nicer on a shelf, but they fight you at the page level and cracks form at the spine within weeks of daily use. Page thickness also matters: thin paper lets ink bleed through and ruins the reverse-side charts. If you plan to keep the planner as a record of your payoff journey — many people do, as a milestone keepsake — durability should outweigh a small price difference.
Progress Visualization
The psychology of debt payoff depends heavily on seeing progress, and planners differ sharply here. Some use colorable charts — debt thermometers, block trackers you fill in after each payment — while others only offer numeric running-balance tables. Visual trackers are not a gimmick: they turn an abstract declining balance into something tangible, which sustains motivation through the boring middle months of a payoff plan. Numeric-only layouts suit spreadsheet-minded users who find coloring tedious. If you have abandoned debt plans before because progress felt invisible, prioritize a planner with strong visual elements over one with more raw data columns.
Multi-Pack Value and Household Use
Think about who else in your household is paying off debt before you buy a single planner. Couples often run separate payoff plans for individually held cards, and multi-packs let each person track their own progress without sharing a cluttered book. A three-pack also serves one person tracking distinct debt categories — credit cards in one, loans in another. The tradeoff is that multi-packs are almost always tracker-only formats with minimal strategy content, so a beginner household may still want one strategy workbook alongside the pack. Buying duplicates of a planner you end up disliking is a wasted expense, so confirm the layout works before stocking up.
Frequently Asked Questions
Should I use a debt snowball or debt avalanche planner for credit cards?
The snowball method pays off your smallest balances first, building motivation through quick wins, and most strategy planners in this roundup are built around it because it has the highest completion rate. The avalanche method targets your highest-interest card first, which saves more money over time but delivers slower emotional payoff. If your credit card balances are similar in size, the two methods converge and it barely matters. Where they diverene is with one large high-interest card sitting alongside several small ones — that is when the avalanche saves real money. Most trackers on this list actually accommodate either method, since they just log payments against each account, so you can choose your sequencing strategy separately from your planner purchase.
Is a paper planner better than a debt payoff app?
Paper planners win on commitment and visibility — writing a payment by hand creates a stronger psychological anchor than tapping a checkbox, and a planner left open on your desk is a constant reminder of the goal. Apps win on automation: they pull balances, recalculate payoff dates, and remove the risk of math errors. The common mistake is assuming one replaces the other; many successful payoff journeys use an app for calculations and a paper planner as the daily accountability layer. If you already ignore notifications on your phone, a paper planner will outperform an app for you. If you hate manual data entry, no planner layout will fix that, and an app may be the better foundation.
Do 90-day payoff planners work for large credit card balances?
Do 90-day payoff planners work for large credit card balances?
They can, but you need to reframe what the 90 days represents. For a large balance, a 90-day planner works best as a series of sprints — you complete one book, buy or restart another, and treat each cycle as a checkpoint rather than a finish line. The risk is discouragement: if you expect a large balance to disappear in one 90-day book and it does not, the planner becomes a reminder of failure instead of progress. Buyers with balances that will take years to clear are better served by open-ended monthly trackers like the Monthly Tracker for Paying Off Your Debts from this lineup. Sprint formats genuinely shine for balances under a few thousand dollars where full payoff in one cycle is realistic.
Can one planner handle credit cards and other loans together?
Most can, but the quality of mixed-debt handling varies a lot. Planners with separate sections per account, like the Debt Tracker for Credit Cards and Loans, handle mixed debt cleanly because each balance gets its own progress page. Weaker designs force all debts into a single shared grid, which gets cramped once you have more than three or four accounts and makes interest-rate comparisons awkward. If your strategy depends on sequencing credit cards against a car loan or student debt, look for a planner with an overview page that lists every debt with its rate and balance side by side. That single summary page is what makes avalanche-style prioritizing possible without a spreadsheet.
Conclusion
The right pick depends on where you are in your payoff journey. For best overall, the Debt Payoff Blueprint: A 90-Day Step-by-Step Plan stands out because it combines strategy, structure, and a realistic sprint timeline in one package. For best value, the 3-Pack Debt Payoff Planner is unbeatable for couples and multi-debt households, provided you bring your own payoff method. For best for beginners, the Debt Payoff Made Simple Planner removes the guesswork with its guided 90-day format, while the Comprehensive Guide suits readers who want deeper education alongside their tracking. For best for large, long-term balances, choose the Monthly Tracker for Paying Off Your Debts over any sprint-format book. Whatever you pick, the planner only works if it opens daily — match the format to your habits, and the debt will follow the plan.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.