Budgeting planners for beginners range from simple monthly trackers to workbooks that teach spending habits. I name the Clever Fox Budget Book 2.0 my best overall pick for its monthly financial-planning focus, while the Achieve Financial Peace Budget Planner stands out for guided debt work and the SKYDUE A6 Budget Binder for envelope-style cash planning. The main tradeoff is between a guided structure that helps you get started and a simpler layout that leaves more room to customize. Undated books offer flexibility, while dated or year-long formats can provide a steadier routine. Read on for how all 15 options compare and which style may fit your habits.

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
Key Takeaways
- Guidance and flexibility are different strengths: Clever Fox centers monthly financial planning, while the Achieve Financial Peace workbook gives debt-focused direction.
- Physical cash planners serve a distinct purpose: The SKYDUE binder pairs expense sheets with zipper envelopes, a more hands-on approach than a bound monthly tracker.
- Undated formats appear across the lineup: They let beginners start at any point, but still require the reader to set a regular check-in routine.
- Storage is not the same as budgeting support: Pocket-equipped SOLIGT and GOLDPEI planners help organize bills or papers, but buyers should still check how much room their chosen layout gives for tracking.
- Weekly and monthly formats suit different habits: Weekly workbooks and trackers call for more frequent attention; monthly planners group decisions into a broader cycle.




| budgeting planners for beginner | Brand | Binding | Format |
|---|---|---|---|
| SOLIGT Undated Budget Planner | SOLIGT | Spiral-bound | Organizer |
| Poluma 12-Month Undated Budget | Poluma | Twin-wire | Undated planner |
| Taja Undated Budget Planner an | — | Spiral-bound | Undated organizer |
| Budgeting With a Purpose: A St | — | — | Weekly workbook |
| Undated 14-Month A5 Budget Pla | KMQOY | Spiral-bound | Notebook and organizer |
| Clever Fox Budget Book 2.0 Mon | Clever Fox | — | — |
| TREES Undated 12-Month Budget | TREES | Spiral-bound, 180° lay-flat | — |
| Taja Undated Monthly Budget Pl | Taja | Spiral-bound | — |
| Kamoy Undated Monthly Budget P | Kamoy | Spiral-bound | — |
| Weekly Budget Planner: A Year- | — | — | Undated weekly budget planner |
| GOLDPEI 12-Month Undated Budge | GOLDPEI | Double spiral | Notebook |
| SOLIGT Undated Budget Planner | SOLIGT | Spiral-bound | Organizer |
| Achieve Financial Peace Budget | — | — | Large size |
| Undated Monthly Budget Planner | snootion | Twin-wire | — |
| SKYDUE A6 Budget Binder with Z | SKYDUE | — | — |
More Details on Our Top Picks
SOLIGT Undated Budget Planner and Monthly Bill Organizer with 12 Pockets
The 12 storage pockets make this a practical choice for beginners who want receipts and bill paperwork near their monthly budget, rather than tucked in a separate folder. Its pages cover income, expenses, savings, debt payments, and bills, giving new budgeters a broad place to record the basics. Compared with the Poluma 12-Month Undated Budget Planner, SOLIGT offers more document storage, while Poluma highlights lay-flat binding and an elastic closure. The tradeoff is that SOLIGT leaves months and budget categories blank, so you must set up the structure yourself before tracking. Month tabs and a portable format help with navigation, but this is better for someone comfortable filling in a template than someone seeking guided instructions.
Pros:- 12 pockets keep bills and receipts with the planner
- Tracks income, expenses, savings, debt payments, and bills
- Undated pages let users start at any point in the year
- Month tabs and a compact format support easy organization and carrying
Cons:- Budget categories and month labels must be filled in by the user
- The planner offers less built-in guidance than a workbook-style option such as Taja
Best for: Beginners who handle paper bills and receipts and want one planner to store documents alongside monthly budget notes.
Not ideal for: First-time budgeters who want prefilled categories or step-by-step prompts, since the pages require setup and manual labeling.
- Brand:SOLIGT
- Format:Organizer
- Calendar type:Monthly, undated
- Size:9.25 x 6.81 inches
- Binding:Spiral-bound
- Pockets:12
- Paper weight:100 gsm
- Cover:Cardboard with faux leather; purple floral
Our verdict“Choose SOLIGT if keeping bill paperwork with a flexible monthly budget matters more than having a prefilled layout.”
Poluma 12-Month Undated Budget Planner and Expense Tracker
Poluma suits beginners who want a repeatable monthly routine more than a place to file a stack of paperwork. Its pages cover budgets, expenses, progress reviews, savings, and debt, so users can record activity and then check whether their plan is working. The twin-wire lay-flat binding keeps the planner open while writing, while an inner pocket and elastic closure help contain loose items. Compared with the SOLIGT planner, Poluma gives greater emphasis to a guided monthly tracking sequence, but SOLIGT’s 12 pockets are more useful for storing bills and receipts. Poluma is designed for one year of use, and the undated pages still require manual entries; it will not automatically track spending or suit someone who wants a reusable, multi-year notebook.
Pros:- Combines monthly budgets, expense tracking, progress reviews, savings, and debt pages
- Undated format allows a flexible start date
- Twin-wire binding lies flat for easier writing
- Elastic closure and inner pocket help keep the planner and loose papers together
Cons:- Designed for one year of tracking rather than ongoing use across multiple years
- All financial activity must be entered manually
- Offers less document storage than SOLIGT’s 12-pocket organizer
Best for: Beginners who want dedicated monthly budget, expense, savings, and debt pages in a planner that lies flat while they write.
Not ideal for: People seeking a long-term reusable record or substantial receipt storage; it covers one year and has only an inner pocket.
- Brand:Poluma
- Format:Undated planner
- Duration:12 months
- Dimensions:6.1 x 8.25 inches
- Binding:Twin-wire
- Audience:Adults
- Storage:Inner pocket and elastic closure
- Tracking pages:Monthly budgets, expenses, progress, savings, and debt
Our verdict“Pick Poluma if a clear monthly tracking routine and lay-flat writing matter more than extensive receipt storage.”
Taja Undated Budget Planner and Expense Tracker, 6.9 x 9.9 Inches, 150 Pages
Taja is the strongest fit here for beginners who want a little help getting started: it includes a budgeting guide alongside pages for income, expenses, savings goals, debt, and bill payments. That added guidance gives it an advantage over SOLIGT, whose blank categories leave more of the setup to the owner. Taja also includes three sticker sheets, an elastic band, and a dual-sided pocket, adding practical ways to mark pages and keep loose notes together. Its 150-page format is larger than a compact option such as Poluma, which may give the layout more room but makes Taja less discreet to carry. Dates still need to be filled in by hand, and the guide’s presence does not remove the need to enter and review finances regularly.
Pros:- Includes a budgeting guide alongside core monthly tracking
- Covers income, expenses, savings goals, debts, and bills
- Three sticker sheets can help mark or distinguish planning sections
- Elastic band and dual-sided pocket provide convenient closure and storage
Cons:- Users must fill in dates themselves
- At 6.9 x 9.9 inches, it is less compact than Poluma’s 6.1 x 8.25-inch format
- Manual tracking still requires consistent entry and review
Best for: New budgeters who want a guide to accompany monthly tracking and appreciate extra room for notes, stickers, and loose papers.
Not ideal for: People who prioritize a small, simple carry-everywhere planner or want a fully dated calendar that needs no setup.
- Format:Undated organizer
- Size:6.9 x 9.9 inches
- Pages:150
- Binding:Spiral-bound
- Weight:0.45 kg
- Included:Budgeting guide and three sticker sheets
- Storage:Dual-sided pocket
- Closure:Elastic band
Our verdict“Choose Taja if you are new to budgeting and want a guide and broad tracking coverage in a roomier planner.”
Budgeting With a Purpose: A Step-by-Step Weekly Workbook for Smarter Spending Habits
This workbook takes a different route from the monthly organizers in this roundup: its weekly structure centers on building spending habits and confidence with money decisions, rather than listing specific monthly tracking pages. That focus may appeal to beginners who want regular reflection and practice, especially if a month-at-a-glance planner feels too broad. Compared with Taja, which identifies concrete areas such as income, debt, bills, and savings, the available description for Budgeting With a Purpose does not name its exercises or worksheets. I would choose it for its stated habit-building approach, not on the assumption that it includes detailed account logs or bill calendars. That limited information makes this a less predictable choice than Poluma or SOLIGT for buyers seeking clearly specified tracking layouts.
Pros:- Weekly structure encourages regular budgeting practice
- Focuses on developing lasting spending habits
- Aims to support confidence in money decisions
- Offers a workbook-oriented alternative to monthly organizers such as Poluma
Cons:- Available product details do not specify its exercises or page layouts
- No stated features confirm dedicated income, bill, savings, or debt logs
- Format and physical specifications are not provided
Best for: Beginners who want a weekly workbook focused on spending habits and money confidence rather than a clearly specified monthly tracker.
Not ideal for: Buyers who need confirmed income, expense, savings, debt, or bill-tracking pages, since those specific exercises are not described.
- Format:Weekly workbook
- Series:The Practical Wealth Series
- Topic:Budgeting and spending habits
- Structure:Weekly
- Stated focus:Building lasting financial habits
- Product details:Specific exercises and physical specifications not provided
Our verdict“Consider this workbook if weekly habit practice is your priority, but choose a detailed tracker if you need confirmed financial log pages.”
Undated 14-Month A5 Budget Planner and Expense Tracker
This A5 planner is a practical match for beginners who want a portable monthly layout without the pockets or extras found in SOLIGT and Taja. Its described pages cover a monthly budget, four expense-tracking pages, a summary, and notes, giving users a straightforward place to record activity and reflect on the month. The spiral binding makes it easier to write across an open page, while the listed 0.23 kg weight supports carrying it along. The product data contains a real ambiguity: the title says 14 months, but the description says the title indicates 12 months, and the cover color is described inconsistently. Compared with Poluma, its specified expense pages and A5 format are useful, but buyers should not assume the duration or cover color is settled.
Pros:- Provides monthly budget, four expense-tracking pages, a summary, and notes
- Undated pages allow users to choose when to start
- A5 size and spiral binding suit carrying and open-page writing
- Listed weight is 0.23 kg
Cons:- Duration is unclear: the title says 14 months while the description refers to 12 months
- Cover color is inconsistently described as green and pink
- No pockets or storage features are specified
Best for: Beginners who want a lightweight A5 planner with separate monthly budget, expense, summary, and notes pages.
Not ideal for: Buyers who need confirmed coverage length, a reliable cover-color choice, or built-in pockets for receipts and bills.
- Brand:KMQOY
- Format:Notebook and organizer
- Duration:Listed as 14 months; conflicting 12-month reference in description
- Date format:Undated
- Paper size:A5
- Binding:Spiral-bound
- Pages:Monthly budget, four expense-tracking pages, monthly summary, and notes
- Weight:0.23 kg
- Cover:Color described inconsistently as green and pink
Our verdict“Choose this planner for a lightweight A5 monthly tracking layout only if the unclear duration and cover details do not affect your choice.”
Clever Fox Budget Book 2.0 Monthly Financial Planner, Rose Gold
The Clever Fox Budget Book 2.0 earns its place for beginners who want one compact book for monthly budgets, daily spending, bills, savings, and debt. Its eight savings trackers and eight debt trackers give longer-term goals room alongside the everyday numbers, while monthly notes pages offer space for reminders that do not fit the printed sections. Compared with the TREES Undated 12-Month Budget Planner, Clever Fox specifies heavier 120 gsm paper and adds a pen loop, ribbon bookmark, receipt pocket, and user guide. That makes it a more supported setup, though the compact 5.3 × 7.7-inch pages leave less writing room than the larger Taja Undated Monthly Budget Planner and Bill Organizer. The dated cadence is monthly, so it suits a steady routine better than someone seeking weekly spending prompts. Its binding type is not specified, which leaves less certainty about how it will handle frequent writing.
Pros:- Combines monthly budgets, daily expenses, bills, savings, and debt tracking.
- Eight savings trackers and eight debt trackers support multiple goals.
- Compact format includes a pen loop, bookmark, receipt pocket, and stickers.
- 120 gsm paper and monthly notes pages add writing support and flexibility.
Cons:- The 5.3 × 7.7-inch format may feel cramped for detailed entries.
- Binding type is listed as unknown.
- Monthly planning may not suit beginners who want a weekly spending structure.
Best for: Beginners who want monthly budget, bill, savings, and debt tracking in a portable book with a user guide and built-in storage.
Not ideal for: People who need generous writing space, weekly spending pages, or confirmed details about the binding.
- Brand:Clever Fox
- Model:CFBB2
- Calendar:Monthly
- Dimensions:5.3 × 7.7 inches
- Pages:120
- Paper:120 gsm
- Cover:Faux leather, rose gold
- Trackers:8 savings trackers and 8 debt trackers
Our verdict“Choose this if you want guided monthly tracking and useful accessories in a compact format, but skip it if writing space is your priority.”
TREES Undated 12-Month Budget Planner
The TREES planner is a sensible first pick for someone who wants to begin budgeting when they are ready, not when a calendar says to start. Its undated 12-month format covers income, expenses, bills, savings, and debt, and the included planning instructions can help a beginner turn those categories into a repeatable monthly routine. The 180° lay-flat spiral binding is a practical advantage over the Clever Fox Budget Book 2.0, whose binding details are not provided; pages stay open while you enter figures. TREES also includes an elastic band, double-sided pocket, and stickers. The tradeoff is space: its 5.5 × 8.5-inch pages are compact, especially compared with the larger Taja planner. It also offers one year of tracking, so someone wanting a longer undated runway will need another book after those 12 months.
Pros:- Undated monthly pages can be started at any point in the year.
- Tracks income, expenses, bills, savings, and debt.
- Spiral binding lays flat for easier writing and review.
- Includes planning instructions, an elastic band, a double-sided pocket, and three sticker sheets.
Cons:- The 5.5 × 8.5-inch pages may limit room for detailed entries.
- The planner covers 12 months rather than providing a longer planning period.
Best for: New budgeters who want a flexible start date, clear planning instructions, and a compact planner that lies flat.
Not ideal for: People who need large pages for detailed notes or want a planner that covers more than 12 months.
- Brand:TREES
- Calendar:Undated monthly
- Duration:12 months
- Dimensions:5.5 × 8.5 × 0.55 inches
- Pages:160
- Binding:Spiral-bound, 180° lay-flat
- Cover:Polypropylene, black
- Features:Elastic band, double-sided pocket, three sticker sheets
Our verdict“Pick TREES if a flexible start date and lay-flat pages matter more than a spacious writing area.”
Taja Undated Monthly Budget Planner and Bill Organizer, Wildflowers
For beginners who find compact planners too cramped, the Taja offers a roomier 6.9 × 9.9-inch format while covering income, expenses, savings goals, bills, and debt. The undated monthly layout means there is no need to wait for a new year to start, and its budgeting guide provides a starting point for readers still learning how to organize their money. Compared with the smaller TREES planner, Taja gives more page area for entries; it also lists a dual-sided pocket, elastic closure, and three sticker sheets for keeping loose notes together. The cost of that extra room is portability: this is a larger organizer, not the easiest choice for a small bag. Dates must be filled in manually, too, and the provided specifications do not identify paper weight or binding details beyond spiral binding.
Pros:- Larger 6.9 × 9.9-inch pages allow more room than the compact TREES planner.
- Undated monthly format can be started at any time.
- Includes a budgeting guide and trackers for income, expenses, savings, bills, and debt.
- Elastic closure, dual-sided pocket, and three sticker sheets help organize loose items.
Cons:- Dates need to be written in by the user.
- Larger dimensions are less convenient for carrying than a compact planner.
- Paper weight is not specified.
Best for: Beginners who want more room for monthly figures and notes, plus a guide to help set up a budget.
Not ideal for: Commuters who prioritize a small, light planner or buyers who want preprinted dates and detailed paper specifications.
- Brand:Taja
- Model:T010-P
- Calendar:Undated monthly
- Dimensions:6.9 × 9.9 inches
- Pages:150
- Binding:Spiral-bound
- Color:A. Wildflowers
- Features:Budgeting guide, elastic closure, dual-sided pocket, three sticker sheets
Our verdict“Choose Taja for a guided, roomier monthly budget layout, and choose TREES instead if portability is more important.”
Kamoy Undated Monthly Budget Planner, B5, Green
The Kamoy combines a B5 writing area with an undated 12-month structure, making it a good fit for beginners who want monthly planning without squeezing figures into small boxes. Its pages cover budgets, income and expenses, bills, savings goals, and debt, so a reader can keep routine spending and longer-term targets in one place. Compared with the TREES Undated 12-Month Budget Planner, Kamoy gives more page area, while still retaining a spiral binding and a year of monthly tracking. Tab stickers help locate sections; an elastic closure, pocket, and metal corner protectors add practical organization and cover protection. The tradeoff is uncertainty about the paper: weight and pen compatibility are not listed. The larger 7.2 × 10-inch size also takes up more space than the Clever Fox Budget Book 2.0.
Pros:- B5 pages provide more writing space than the compact TREES planner.
- Undated 12-month format can begin at any time.
- Includes budget, income, expense, bill, savings, and debt tracking.
- Spiral binding, tab stickers, pocket, elastic closure, and metal corner protectors support regular use.
Cons:- The 7.2 × 10-inch format is less portable than smaller options such as Clever Fox.
- Paper weight and compatibility with different pens are not specified.
Best for: Beginners who want a full-year, undated monthly system with room for detailed figures and notes.
Not ideal for: People who need a compact carry-around planner or want confirmed paper weight and pen compatibility.
- Brand:Kamoy
- Calendar:Undated monthly
- Duration:12 months
- Dimensions:7.2 × 10 inches (B5)
- Thickness:0.6 inches
- Binding:Spiral-bound
- Cover:Cardboard, green
- Features:Elastic closure, pocket, metal corner protection, tab stickers
Our verdict“Choose Kamoy if you want a spacious, flexible 12-month planner and can accept unknown paper specifications.”
Weekly Budget Planner: A Year-Long Undated Spending Tracker
This planner’s defining difference is its weekly spending focus, a useful alternative for beginners who find monthly totals too distant to guide everyday choices. An undated format lets the reader begin at any point, and the stated one-year duration offers a defined planning period. Compared with the monthly Clever Fox Budget Book 2.0, this approach may make it easier to review spending habits more often; the tradeoff is that the supplied product details do not say whether it also includes bill, savings, or debt pages. Its page layout, size, binding, and extra features are also unspecified, so I can’t rank it as highly for guided budgeting or organization as the TREES planner, which lists planning instructions and storage features. This is a narrow pick for someone seeking a weekly tracker, not a clearly documented all-in-one financial planner.
Pros:- Weekly focus supports more frequent spending reviews than a monthly-only format.
- Undated format allows a flexible start date.
- Designed for a one-year tracking period.
Cons:- Product details do not describe its page layout or specific tracking sections.
- No information is provided about size, binding, paper, or storage features.
- It may not cover bills, savings, and debt in the same book.
Best for: Beginners who want to check spending week by week and prefer an undated planner with a one-year duration.
Not ideal for: Budgeters who need confirmed monthly budget, bill, savings, or debt sections, or want details about page layout and materials before choosing.
- Format:Undated weekly budget planner
- Duration:One year
Our verdict“Pick this only if weekly spending check-ins are your main need; choose a more fully specified option like TREES for broader budgeting guidance.”
GOLDPEI 12-Month Undated Budget Planner with Monthly Pockets
For a beginner who wants bills and receipts to live alongside each month’s budget, the GOLDPEI pairs planning pages with 12 monthly storage pockets. Its income and expense logs include a running balance, which helps make each entry’s effect on available funds easier to follow. Budget, bill, savings, and debt trackers also give a new budgeter several ways to organize money without choosing separate notebooks. Compared with the smaller SOLIGT Undated Budget Planner and Bill Organizer with 12 Pockets, GOLDPEI is wider at 7.2 x 10 inches, offering a roomier page format but taking up more bag or desk space. The undated 12-month layout lets buyers start whenever they’re ready. The tradeoff is that this is still a handwritten system: it requires regular updates and offers no listed prompts for choosing budget categories.
Pros:- 12 pockets keep bills, receipts, and reminders sorted by month
- Running balance helps connect expense entries to remaining funds
- Budget, bill, savings, and debt trackers cover several beginner needs
- Undated pages allow starting at any time
Cons:- The 7.2 x 10-inch format is less compact than smaller options such as the SOLIGT organizer
- No listed guided prompts for setting categories or building a budgeting routine
- A handwritten planner depends on consistent manual updates
Best for: Beginners who want a year of budgeting pages plus a dedicated place to file monthly bills, receipts, and reminders
Not ideal for: People who need a highly guided budgeting method, prefer digital tracking, or want a compact planner for a small bag
- Brand:GOLDPEI
- Format:Notebook
- Planning period:12 months, undated
- Size:7.2 x 10 inches
- Cover:Hardcover
- Binding:Double spiral
- Pockets:12 monthly storage pockets
- Color:Green
Our verdict“Choose GOLDPEI if you want room for both monthly money tracking and the paperwork that goes with it.”
SOLIGT Undated Budget Planner and Bill Organizer with 12 Pockets
The SOLIGT Undated Budget Planner and Bill Organizer brings income, expenses, savings, debt, bills, and financial goals into one organizer, while colored month tabs make sections easier to find. Its 9.25 x 6.81-inch format is more portable than the larger Achieve Financial Peace Budget Planner, though that product’s large-size format may suit writers who want more room. Twelve pockets give this pick a practical role for someone who sorts paperwork by month, and undated pages remove the pressure to start in January. The 100 gsm paper and hardcover add substance to a portable format. Its main beginner hurdle is that budget categories must be filled in by the user; the planner records a system the buyer creates rather than supplying one. The page size may also feel tight for lengthy notes.
Pros:- Tracks income, expenses, savings, debt, bills, and financial goals in one organizer
- 12 pockets and colored month tabs help separate monthly records
- Undated pages support a flexible start date
- Hardcover and 100 gsm paper add structure to its portable format
Cons:- Budget categories must be chosen and entered by the user
- The 9.25 x 6.81-inch pages may limit space for detailed notes
- At 0.3 kg, it is not the lightest option in this group
Best for: Beginners who want a portable, tabbed organizer for monthly budgets, bills, savings, debt, and receipts
Not ideal for: People who want pre-filled budget categories, generous writing space, or a larger workbook for detailed planning
- Brand:SOLIGT
- Format:Organizer
- Calendar type:Undated
- Size:9.25 x 6.81 inches
- Binding:Spiral-bound
- Paper weight:100 gsm
- Pockets:12
- Included:Colored month tabs
Our verdict“Pick SOLIGT if you want a portable, tabbed planner with monthly pockets and are comfortable defining your own categories.”
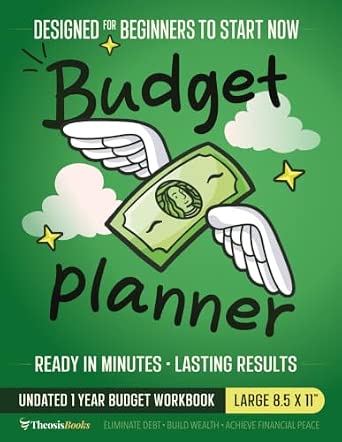
Achieve Financial Peace Budget Planner: 12-Month Debt Workbook for Beginners
The Achieve Financial Peace Budget Planner puts debt management at the center of a 12-month budgeting plan, making it the clearest fit here for a beginner whose main goal is to organize finances while working through debt. Its stated beginner focus gives it a more purpose-driven role than the GOLDPEI 12-Month Undated Budget Planner, which offers multiple trackers and monthly pockets but is described less specifically as a debt workbook. The large-size format may give planning and tracking more room, a contrast with the compact snootion A5 planner, which is easier to carry but necessarily smaller. The available product details do not specify page count, binding, date format, or particular debt exercises, so buyers have less information about its layout before choosing it. It is best for someone who values the debt-planning focus over storage features.
Pros:- Designed specifically for beginners
- Covers a full 12 months
- Debt management is a stated purpose, not just a secondary tracker
- Large-size format is intended to provide room for planning and tracking
Cons:- Available details do not specify whether the planner is dated or undated
- No page count, binding, or paper details are provided
- No storage pockets or specific bill, savings, or expense sections are listed
Best for: Beginners seeking a year-long workbook with a specific focus on budgeting and managing debt
Not ideal for: Buyers who need undated start dates, monthly document pockets, or confirmed details about page layout and tracking sections
- Duration:12 months
- Format:Large size
- Purpose:Budget planning and debt management
- Experience level:Beginners
Our verdict“Choose this workbook if debt planning is your main beginner goal and you do not need the documented pocket features of GOLDPEI or SOLIGT.”
Undated Monthly Budget Planner and Expense Tracker, A5, Silver
The snootion A5 planner is the compact paper-first choice for beginners who want monthly budgeting pages without carrying a full-size organizer. At 8.6 x 5.9 inches and 0.18 kg, it is easier to tuck into a bag than the larger GOLDPEI, though GOLDPEI’s 7.2 x 10-inch format gives more room for writing and includes 12 pockets for paperwork. Snootion covers goals, budgets, bills, savings, debts, and daily expenses across an undated 12-month plan, so a buyer can start at any point and track more than one part of their finances. Twin-wire binding lays flat for writing, while 100 gsm paper offers a substantial writing surface. The tradeoff is its 100-page limit and monthly focus: it is less suited to extensive notes or buyers looking for weekly planning.
Pros:- Compact A5 size and 0.18 kg weight suit portable use
- Sections cover goals, budgets, bills, savings, debts, and daily expenses
- Undated 12-month format allows a flexible start
- Twin-wire binding lays flat for writing
Cons:- 100 pages may limit room for extended notes or additional tracking
- Monthly budgeting format may not suit people who need weekly planning
- Unlike GOLDPEI, it has no listed pockets for storing monthly paperwork
Best for: Beginners who want a lightweight, undated monthly money planner that fits in a handbag or backpack
Not ideal for: People who need lots of writing space, weekly planning, or pockets for keeping bills and receipts with their records
- Brand:snootion
- Planning period:12 months
- Date format:Undated
- Size:A5 (8.6 x 5.9 inches)
- Page count:100 pages
- Paper weight:100 gsm
- Binding:Twin-wire
- Cover material:Polypropylene
Our verdict“Choose snootion if portability and a broad set of monthly tracking sections matter more than extra pages or document storage.”
SKYDUE A6 Budget Binder with Zipper Envelopes and Expense Sheets
Unlike the bound monthly planners in this roundup, the SKYDUE A6 Budget Binder is built around separating money and small items into eight zipper pockets. It comes with 12 expense sheets and category stickers, giving a beginner a tangible way to divide cash and record spending without setting up a separate notebook. Compared with the SOLIGT Undated Budget Planner and Bill Organizer, which offers 12 monthly pockets and broader income, savings, and debt tracking, SKYDUE is more focused on a portable envelope-style routine than year-long financial planning. Its A6 size, pen loop, and storage compartments favor carrying it in a bag, but the 0.5-inch capacity and small envelopes limit what it can hold. The available details also do not specify a full 12-month planning structure, so it suits hands-on cash organization better than complete annual budgeting.
Pros:- Eight zipper pockets support category-based cash organization
- Includes 12 expense sheets and three category sticker sheets
- Compact A6 binder includes storage compartments and a pen loop
- Six-ring format keeps the included sheets together
Cons:- A6 size and 0.5-inch capacity limit cash and paperwork storage
- Zipper pockets may not fit bulky items
- Does not list the broader monthly savings, debt, and bill tracking found in SOLIGT
Best for: Beginners who want to divide cash by category, carry expense sheets, and keep a small budgeting kit together
Not ideal for: People who need a full year of monthly budget pages, larger document storage, or detailed tracking of savings and debt
- Brand:SKYDUE
- Size:A6
- Dimensions:7.5 x 5.3 inches
- Binder material:Faux leather
- Ring count:6
- Zipper pockets:8
- Expense sheets:12
- Capacity:0.5 inches
Our verdict“Choose SKYDUE if you want a compact cash-envelope system, not a full-size monthly planner with broad financial trackers.”
How We Picked
I ranked these budgeting planners for beginners by how clearly their format supports common first steps: setting a plan, recording spending, keeping bill information together, and reviewing progress. I also weighed practical fit, including whether a planner is undated, weekly or monthly, pocket-equipped, or designed as a binder. Those details matter because beginners often need a format that matches the routine they can maintain, not the one with the longest feature list.
The order reflects the balance of beginner guidance, everyday usability, and flexibility. Planners with a clear general-purpose role lead, while specialized options rank higher for readers who specifically want debt exercises, weekly oversight, or cash envelopes. Similar-looking products are separated by their stated format and purpose; without verified page layouts or material details, I do not assume that one is more durable or easier to write in than another.
| budgeting planners for beginner | Binding |
|---|---|
| SOLIGT Undated Budget Planner | Spiral-bound |
| Poluma 12-Month Undated Budget | Twin-wire |
| Taja Undated Budget Planner an | Spiral-bound |
| Budgeting With a Purpose: A St | — |
| Undated 14-Month A5 Budget Pla | Spiral-bound |
| Clever Fox Budget Book 2.0 Mon | — |
| TREES Undated 12-Month Budget | Spiral-bound, 180° lay-flat |
| Taja Undated Monthly Budget Pl | Spiral-bound |
| Kamoy Undated Monthly Budget P | Spiral-bound |
| Weekly Budget Planner: A Year- | — |
| GOLDPEI 12-Month Undated Budge | Double spiral |
| SOLIGT Undated Budget Planner | Spiral-bound |
| Achieve Financial Peace Budget | — |
| Undated Monthly Budget Planner | Twin-wire |
| SKYDUE A6 Budget Binder with Z | — |
Factors to Consider When Choosing Budgeting Planners For Beginners
Before choosing, decide what you want the planner to change in your routine: remembering bills, seeing where money goes, working through debt, or managing cash. A beginner-friendly format is one you will use repeatedly, even if it has fewer sections than a more elaborate book.
Choose a check-in rhythm you can maintain
A monthly layout can be easier to keep up with if you prefer to plan bills and spending in one sitting. A weekly tracker gives you more frequent chances to catch overspending, but it also asks you to return to the book more often. A common mistake is choosing the most detailed schedule without checking whether it fits your calendar. Think about when you naturally review money—on payday, once a week, or at month-end—and match the planner’s rhythm to that habit. If you are uncertain, a flexible undated format can help you begin without waiting for a new year.
Separate tracking from instruction
Some planners mainly provide places to record income, bills, and expenses; others guide you through exercises or a particular goal. If you already know how you want to budget, a straightforward tracker may be less distracting than a workbook. If you need help forming a routine or organizing debt priorities, guided prompts may be worth the extra structure. Do not assume that a planner with more pages will teach more: check whether its stated focus matches the question you need help answering. Beginners can also start with a simple tracker and add learning resources separately.
Decide whether physical cash belongs in your system
Envelope binders and pocket-equipped planners can help keep cash, receipts, or bill papers in one place. They work best when you actually use cash categories and are willing to update the accompanying expense sheets. If most spending happens by card or online, envelopes may add steps without improving your visibility. A pocket is a storage feature, not a substitute for recording transactions or reviewing totals. Choose this format for a cash-management routine, rather than for appearance alone.
Check the format against your writing and storage habits
Size affects where a planner can live and how much space you may have to write, though a product name alone cannot tell you how its pages are laid out. A compact book or binder may travel more easily, while a larger format can be preferable if you want a dedicated desk planner. Before buying, look for page previews and confirm that the layout has room for the categories you use. Beginners often overlook this and later find that their real-life expenses do not fit the printed fields. If you need custom categories, prioritize flexible or open-ended sections.
Treat undated pages as flexibility, not a reminder system
An undated planner lets you start whenever you are ready and skip periods without leaving a dated book visibly unfinished. That flexibility can reduce pressure, but it will not prompt you to make regular entries. Set a recurring reminder or connect your check-in to an existing routine, such as payday. If you prefer a guided cadence, a year-long or weekly structure may give you a clearer sequence to follow. The best choice depends on whether you need freedom to restart or a schedule that keeps you accountable.
Pay for a feature you will use, not a longer checklist
A specialized workbook, cash binder, or planner with pockets can be worthwhile when its extra structure addresses a real need. If you only want to record income and bills, added sections may create clutter rather than value. Compare the planner’s intended use with your current challenge before choosing a more involved format. It is also sensible to begin with a manageable system and change formats only when you can name what is missing. That approach limits the common beginner mistake of buying an elaborate planner and abandoning it because maintaining it feels like another task.
Frequently Asked Questions
Should I choose a monthly planner or a weekly spending tracker as a beginner?
Choose monthly if your main need is organizing bills, income, and broad spending plans in one regular review. Choose weekly if you want to monitor purchases more often and are willing to make entries throughout the month. Neither schedule is automatically easier: the better fit is the one you can keep using. If you are unsure, consider how often you already check your bank activity and use that as your starting rhythm.
Is an undated budgeting planner a good choice if I tend to forget to budget?
An undated planner makes it easier to begin late or restart after a missed period, but it does not provide reminders by itself. Pair it with a calendar alert, a payday routine, or another cue you already notice. If a printed sequence helps you stay accountable, a year-long or weekly format may feel more structured. The key distinction is flexibility versus built-in cadence, not whether one type is universally better.
Do I need a planner with pockets or zipper envelopes?
Pockets are useful if you keep receipts, bill papers, or cash categories together with your budget notes. A zipper-envelope binder makes the most sense when you actively plan to separate cash for spending categories. If you manage money mainly through cards and online accounts, those storage features may add bulk without helping you track transactions. Choose based on how you handle money day to day, not simply on the number of included pockets.
Should I buy a debt workbook or a general expense tracker first?
A debt-focused workbook is a better starting point if organizing balances and repayment goals is your main budgeting challenge. A general expense tracker suits someone who first needs to understand income, bills, and everyday spending. Some beginners need both functions, but trying to tackle every financial goal at once can make a new routine harder to sustain. Start with the tool that addresses the decision you need to make most often, then add another system if a clear gap remains.
How can I tell whether a planner has enough space for my budget?
Check page previews for the number of spending categories, writing areas, and room for notes rather than relying only on the planner’s title or size. List the categories you actually use, including irregular costs, and compare them with the visible layout. If the printed fields seem restrictive, look for blank or customizable sections. A planner that captures your real expenses is more useful than one with an attractive format that forces you to combine unrelated categories.
Conclusion
My best overall recommendation is the Clever Fox Budget Book 2.0 for beginners seeking a monthly financial-planning format. For best value in a straightforward format, compare the undated trackers—especially the Poluma and Taja options—and choose by layout and size details that suit your routine, since their names alone do not establish a clear feature advantage. The Achieve Financial Peace Budget Planner is my pick for a beginner who wants debt-focused guidance, while the SKYDUE A6 Budget Binder fits someone who budgets with physical cash. For more frequent spending check-ins, consider the weekly workbook or tracker; for bill papers and storage, look at pocket-equipped choices such as SOLIGT or GOLDPEI. I would pay for specialized features only when they match a habit you plan to keep.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.