TL;DR

Get smart everyday buys delivered free with Prime
- Fast, free delivery on millions of items
- Prime Video, Amazon Music and more included
- Member-only deals all year
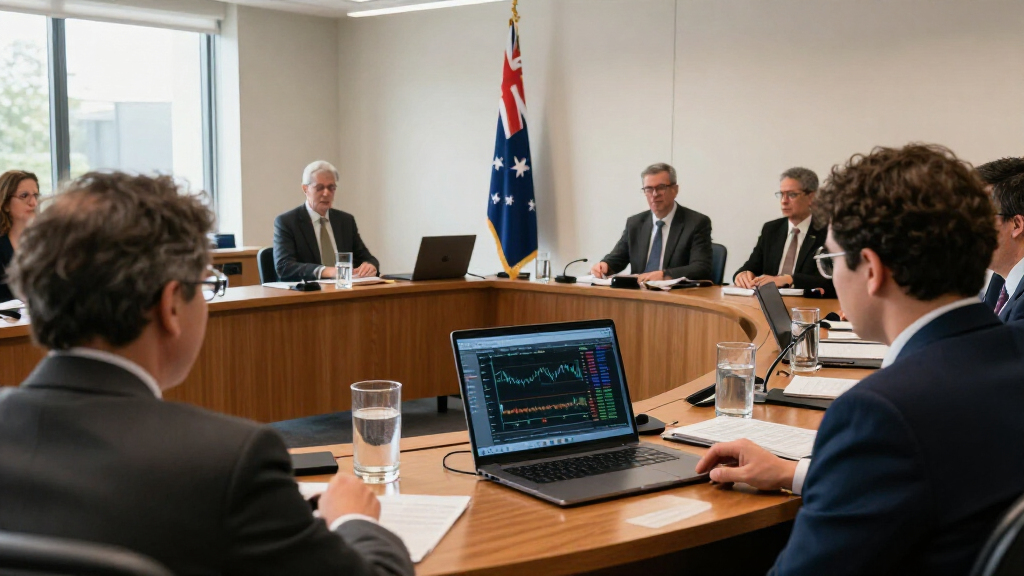
RBA Governor Michele Bullock told a Senate committee on 28 October that inflation is likely to be higher than the Reserve Bank’s August forecast, as global energy costs and domestic capacity pressures persist. The cash rate target has risen by 100 basis points this year, including a 25-basis-point increase since the committee’s previous hearing.
Reserve Bank of Australia Governor Michele Bullock told a Senate committee on 28 October that inflation is likely to run higher than the central bank expected in August, citing a renewed rise in global energy prices and persistent pressure on the Australian economy’s capacity. She said the Monetary Policy Board had lifted its cash rate target by 25 basis points since the committee’s June hearing, taking this year’s cumulative increase to 100 basis points.
In her opening statement to the Senate Economics Legislation Committee’s supplementary budget estimates hearing, Bullock said the Board’s monetary policy goal was to bring inflation back to the midpoint of its 2–3 per cent target range, while also taking account of its full employment objective. Inflation had fallen from a peak of 7.9 per cent at the end of 2022 and was within the target range for a period in 2024 and 2025, but it picked up in the second half of 2025 and has remained above target. Bullock put recent year-ended inflation at around 3.5 to 4 per cent.
The RBA’s latest published forecasts, issued in its August Statement on Monetary Policy, had inflation returning to around the target midpoint in late 2027. Bullock said developments since then indicated that inflation would likely be higher than the August base case. The conflict in the Middle East has intensified again, she said, pushing oil and other energy prices well above levels assumed in those forecasts. Higher fuel and transport costs can affect prices directly and indirectly if businesses pass increased costs on to customers.
Bullock also pointed to elevated short-term inflation expectations and other international cost pressures, including demand for supply-constrained technology linked to the AI boom and price pressures associated with extreme weather. She said domestic factors remained part of the problem: underlying inflation was elevated, the labour market appeared tighter than the Bank had previously judged, and weak productivity growth limited how quickly the economy could expand without adding to price pressure.
Higher Inflation Risks Shape Rate Decisions
The warning matters because it signals that the inflation outlook has become less favourable since the RBA’s August assessment, even as economic growth is slowing. If price pressure stays elevated, the Board may need to keep monetary policy restrictive for longer or consider further action. Bullock did not announce a new rate decision in this opening statement; the 25-basis-point rise she described had already been made.
For households and businesses, the effects of rate increases arrive over time. Bullock said the full impact of recent increases had yet to be felt in domestic activity. She also said household spending growth had moderated only gradually and business investment had picked up strongly, mostly due to spending on data centres. The statement presents a difficult balance for policymakers: demand needs to ease enough to reduce inflation, while the Board’s stated objective also includes full employment.
Products Worth Considering

Samsung 27 Odyssey OLED G5 (G50SF) QHD QD-OLED Gaming Monitor

Samsung 27-Inch Odyssey QD-OLED G8 4K 240Hz Gaming Monitor

LG UltraGear 27-Inch QHD OLED Gaming Monitor, 240Hz, 0.03ms, G-SYNC Compatible, FreeSync Premium Pro, HDMI 2.1
As an affiliate, we earn on qualifying purchases.
Inflation’s Return Above Target
The RBA’s monetary policy framework aims to return inflation to the midpoint of the 2–3 per cent target range while supporting full employment. Bullock said the Board allows flexibility over the timeframe for returning inflation to target, but cautioned that inflation remaining above target for too long could become embedded in expectations and influence wage- and price-setting.
Inflation fell substantially after monetary policy tightened during 2022 and 2023. It then moved back above the target range from the second half of 2025. In August, the Bank forecast a return to around the midpoint in late 2027 and judged the risks to that outlook were tilted upwards. Bullock’s October statement updates that assessment, saying some domestic and international risks had materialised or were materialising. She said central banks in other advanced economies were also raising rates or signalling they might do so if needed.
The statement also addressed the RBA’s wider responsibilities, including the payments system, banking services for government agencies and banknote distribution. The opening remarks said Bullock and her colleagues were attending to answer committee questions, but the main economic update focused on inflation, monetary policy and the outlook.
“Inflation will therefore likely be higher than was our base case in August.”
— Michele Bullock, RBA Governor
Forecast Path Remains Unsettled
The statement does not provide a revised inflation forecast or specify when inflation will return to the target midpoint. The August projection of a return in late 2027 remains the latest published forecast cited by Bullock, but she said inflation was likely to be higher than that forecast’s base case. The size and duration of the effect from the Middle East conflict, energy prices and other global cost pressures are not quantified in the opening remarks.
Nor does the statement set out what the Board will decide at its next meeting. Bullock said the labour market had recently softened somewhat, with unemployment rising a little more than expected, while describing it as tighter than the Bank had previously assessed. The balance between inflation, demand, employment and the delayed effects of earlier rate increases remains uncertain.
Committee Questions and Updated Outlook
Bullock and her colleagues were due to answer questions from the Senate Economics Legislation Committee at the supplementary budget estimates hearing. Their responses may provide further detail on the Bank’s assessment of inflation, growth, employment and the effects of higher energy prices.
The next key indicator will be the RBA’s subsequent public assessment of the economy and inflation, including any updated forecasts and monetary policy decision. Until then, the August forecast remains the latest published projection, while Bullock’s statement signals that the outlook has shifted towards higher inflation risks.
Key Questions
What did Michele Bullock tell the Senate committee?
She said inflation was likely to be higher than the RBA’s August base-case forecast, pointing to global energy costs and domestic capacity pressures.
How much has the cash rate target risen this year?
Bullock said the Board had increased the target by 100 basis points cumulatively this year, including a 25-basis-point rise since the committee’s June hearing.
What is the RBA’s inflation target?
The Board aims for inflation to return to the midpoint of its 2–3 per cent target range, while also taking account of full employment.
When does the RBA now expect inflation to return to target?
The latest published forecast cited in the statement projected a return to around the midpoint in late 2027. Bullock said the outlook had since worsened, and the statement did not provide a revised date.
Did Bullock announce another interest rate rise?
No. Her opening statement reported the Board’s previous 25-basis-point increase and the year’s cumulative 100-basis-point rise; it did not announce a new rate decision.
Source: bis.org