TL;DR

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
A Which? analysis of 72 UK home insurance policies has identified five winter risks that standard cover may not pay out on, including accidental storm damage, groundwater flooding and pest removal. The warning comes as the ABI urges homeowners to prepare for a potentially stormier winter linked to El Niño. Weather-related home claims topped £200m between January and April 2026, the first time that mark has been passed.
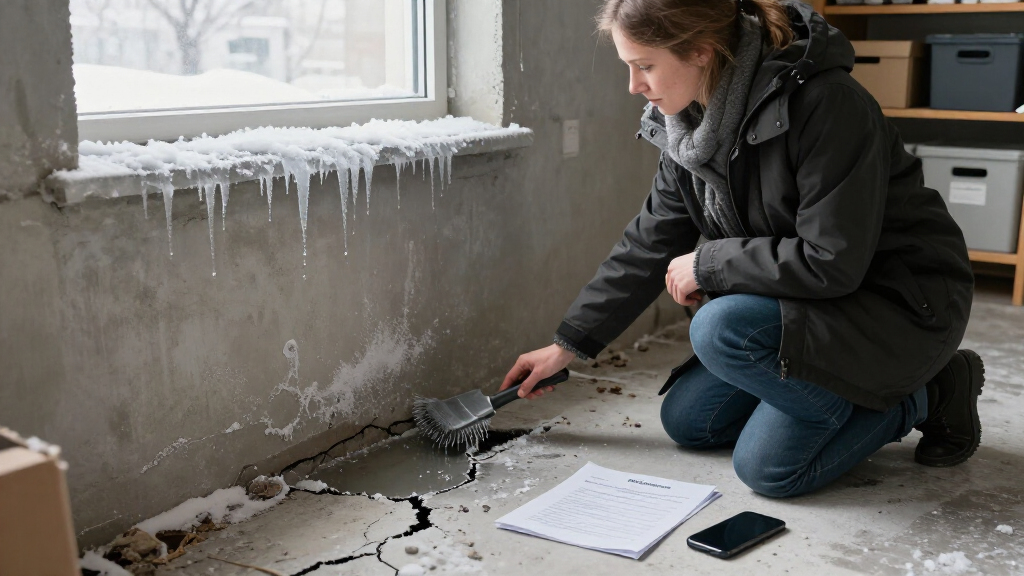
Standard home insurance policies leave winter-related gaps that could leave homeowners paying for damage themselves, according to a Which? analysis of 72 policies from 30 providers. The consumer group identified five seasonal risks — storm damage from poor maintenance, groundwater flooding, unoccupied-home pipe bursts, boiler breakdowns and rodent infestations — where standard cover may fall short. The warning comes as the Association of British Insurers (ABI) urges homeowners to prepare for strong winds and heavy rain linked to a possible ‘super El Niño’ weather pattern.
The report follows a costly spell of winter weather. According to the ABI, weather-related claims for damage to homes and possessions topped £200m between January and April 2026 — the first time they have passed that mark — after the UK was hit by seven named storms last autumn and winter.
Which?’s policy analysis, conducted in the summer, found that only 25% of policies included accidental damage cover as standard, with most selling it as an optional extra. That matters because insurers typically reject claims where damage results from wear and tear, such as water entering through a poorly maintained roof. Only 42% of policies cover gradual groundwater flooding, and just 18% include home emergency cover as standard — the add-on that pays for urgent tradesperson callouts, including rodent removal.
On pipes, coverage is strong: 99% of policies analysed pay out for pipes damaged by freezing or sudden temperature changes. However, claims can fail if the home was unoccupied when the loss occurred, or if the leak resulted from poor maintenance, including corrosion, rust or inadequate grout or sealant. Of policies offering home emergency cover as an optional extra, 97% include vermin and pest removal, Which? found.
Why These Coverage Gaps Cost Homeowners
Winter damage is among the most expensive risks a household faces. Storms and floods can cause thousands of pounds’ worth of damage, and burst pipes can ruin belongings both inside and outside the home. The Which? findings show that the circumstances of the damage — not just the event itself — often determine whether a claim succeeds.
The distinction between sudden incidents and gradual problems is central. A storm tearing off a roof is typically covered; water entering through a roof the homeowner failed to maintain is not. Which? also flagged ‘contents in the open’ caveats: movable items left outside, such as garden furniture and barbecues, may not be covered if they were not properly secured before a storm.
Rodents illustrate a further gap. Saga research found 38% of homeowners have encountered mice at their property and 20% have seen rats, yet 15% wrongly believe standard home insurance covers pest removal. While removal is usually tied to home emergency cover, buildings insurance should generally pay for resulting damage — so chewed wires might not be covered, but a fire they cause should be.
The El Niño Warning Behind the Report
The ABI has urged homeowners to prepare for strong winds and heavy rain that forecasters associate with the El Niño weather phenomenon, which Which? notes could bring the UK more storms than usual this winter if experts’ predictions prove correct.
Last season set a benchmark for winter losses. The seven named storms that hit the UK drove weather-related home claims above £200m between January and April 2026, according to the ABI — a record for that measurement period. Which?’s analysis of 72 policies from 30 providers was conducted in the summer and underpins the coverage figures cited throughout the report.
“Homeowners are being urged to prepare for strong winds and heavy rain caused by the weather phenomenon.”
— Association of British Insurers (ABI)
What the Forecast and Policies Leave Unanswered
It remains uncertain whether this winter will actually bring above-normal storm activity to the UK. Which? itself hedges, saying only that ‘if experts are right’ the super El Niño could produce more storms than usual.
Policy coverage also varies between providers. The percentages in the Which? analysis apply to the 72 policies surveyed in the summer, and individual policy terms — including exclusions for unoccupied homes, gradual groundwater build-up and maintenance-related damage — differ. Homeowners should check their own policy documents rather than assume the survey averages apply to them.
Steps Homeowners Can Take Before Winter
Which? advises homeowners to review their policy extras — accidental damage cover, home emergency cover and garden cover — before bad weather arrives, and to bring valuable outdoor items indoors when storms are forecast. Maintaining roofs, pipework and sealants reduces the risk of claims being rejected on wear-and-tear grounds.
For those needing cover, Which? suggests comparing policies using its customer scores, available through comparison services such as MoneySuperMarket. Homeowners who need to claim should contact their insurer promptly and document damage, the report adds. Insurers’ claims data for the coming winter will show whether the El Niño forecast materialises.
Key Questions
Does standard home insurance cover storm damage?
Yes, buildings insurance generally covers damage from hail, wind, rain, snow and ice, including broken roofs, burst pipes, falling trees and power cuts. However, claims can be rejected if the damage stems from wear and tear or poor maintenance, and accidental damage cover — included in only 25% of policies analysed by Which? — is often needed for those cases.
Is flood damage covered by home insurance in the UK?
Flood cover is usually included as standard with buildings insurance, even in high-risk areas, and typically covers repair costs, temporary accommodation and contents. But gradual groundwater flooding is excluded from many policies — Which? found only 42% of those analysed cover it.
Will insurance pay for burst pipes in freezing weather?
Which? found 99% of policies analysed pay out for pipes damaged by freezing or sudden temperature changes. Claims may fail if the home was unoccupied at the time, or if the leak resulted from poor maintenance such as corrosion, rust or inadequate grout or sealant.
Does home insurance cover mice and rat infestations?
Not usually. Rodent removal is typically included in home emergency cover, which only 18% of analysed policies include as standard — though 97% of policies offering it as an optional extra include pest removal. Buildings insurance should generally cover damage caused by rodents, such as a fire from chewed wires, even if the chewed wires themselves are not covered.
What is home emergency cover and do I need it?
Home emergency cover pays for a tradesperson to attend your property quickly in a crisis, such as a sudden leak or boiler breakdown. Which? found it is rarely part of standard home insurance, with most providers offering it as an optional extra. It can be useful in winter for urgent heating and plumbing problems.
Source: rss
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.